定期寿险
- 标准
- 加费
- 除外(通常不出现)
- 延期(通常不出现)
- 拒保
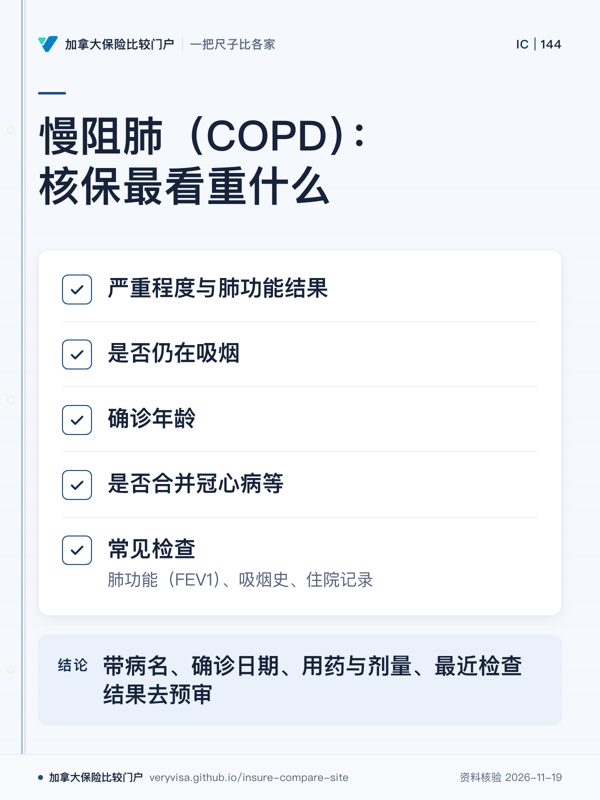
轻度、已戒烟可能标准或小幅加费;中重度加费;重度或仍吸烟多拒保。
✅官方依据强弱:两份以上公开核保指南一致
呼吸 · ICD-10 J44
多与长期吸烟有关的慢性肺病,气流受限、逐渐加重;戒烟和吸入药能减慢进展。
轻度、已戒烟可能标准或小幅加费;中重度加费;重度或仍吸烟多拒保。
与定期寿险评估方法相同:轻度、已戒烟可能标准或小幅加费;中重度加费;重度或仍吸烟多拒保。
公开指南显示重疾多加费或拒保。
多除外呼吸相关失能或加费;重度拒保。
轻度影响小;中重度会影响将来自理,加费或拒保。
要填问卷的计划常把这个病和在用药除外,或不保;保证承保计划不问健康但药物保障少。
看出发前是否稳定(没换药、没新症状、没新检查);不稳定则这个病不赔;年长者答问卷定价,严重者可能不保。
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
下面几家公司的公开核保指南写到了这个病(只列有公开依据的);各家问卷的回看年限、家族史年龄线等对比见:各保险公司怎么问、怎么核.
把病名、确诊日期、用药与剂量、最近检查结果带给持牌顾问,请他先做预审再正式投保。
各公司核保不同,以核保结果为准。本页是一般信息,不是个人医疗或投保建议;病与药的介绍只引官方来源。
先看导读,再看图;点图放大、左右翻页,每张卡都有可分享的详情页。卡上每个字都出自本站正文,不列费率。
价格是个人化的
保费按年龄、性别、是否吸烟和健康状况报价,本站不列费率。持牌保险顾问可在多家公司之间比较报价(可报价的公司以其签约为准),把条款差异列在同一页上。
询价前要准备什么 →Health and insurability atlas / By condition
Lungs and breathing · ICD-10 J44
COPD (chronic obstructive pulmonary disease)
A long-term lung disease, usually linked to smoking, that limits airflow and slowly worsens; quitting smoking and inhalers slow it down.
Mild cases who have quit may be standard or lightly rated; moderate to severe are rated; severe or still smoking usually decline.
Assessed the same way as term life: Mild cases who have quit may be standard or lightly rated; moderate to severe are rated; severe or still smoking usually decline.
A public guide shows critical illness is usually rated or declined.
Usually respiratory exclusion or rating; severe cases declined.
Mild has little impact; moderate to severe affects future independence and is rated or declined.
Medically underwritten plans often exclude this condition and its medications, or decline; guaranteed-issue plans ask no health questions but cover fewer drugs.
Depends on stability before departure (no medication changes, new symptoms or tests); if unstable, that condition is excluded; older travellers answer questions that set the price, and serious cases may not be accepted.
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
These insurers' public underwriting guides cover this condition (only those with a public basis are listed); the side-by-side of look-back years, family-history ages and more is here: How insurers ask and underwrite, side by side.
Bring the condition, diagnosis date, medications and doses, and recent test results to a licensed advisor and ask for a pre-assessment before a formal application.
Underwriting differs by insurer; the insurer’s decision is final. General information only, not personal medical or insurance advice; condition and medication descriptions cite official sources.
