高血压
- 标准
- 加费(通常不出现)
- 除外(通常不出现)
- 延期(通常不出现)
- 拒保(通常不出现)
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
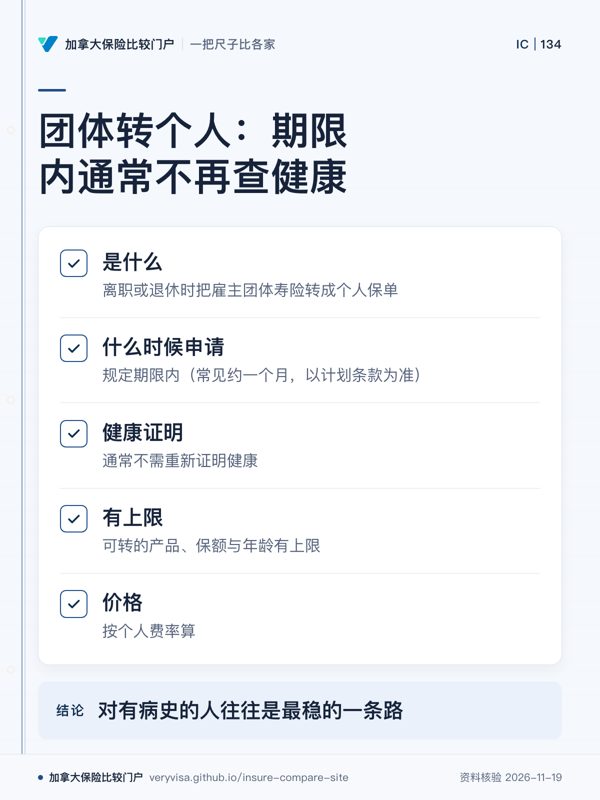
离职或退休时把雇主团体寿险(有时含健康)转成个人保单。
在规定期限内(常见约一个月,以计划条款为准)申请,通常不需重新证明健康——对有病史的人往往是最稳的一条路;但可转的产品、保额与年龄有上限,价格按个人费率算。
这个险种可能出现的结果
健康良好的人可比较「重新核保买个人保单」是否更便宜。
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
在计划规定期限内转个人,通常不必重新证明健康;产品与保额有限,以计划条款为准。
依据:两份以上公开核保指南一致
各公司核保不同,以核保结果为准。本页是一般信息,不是个人医疗或投保建议;病与药的介绍只引官方来源。
先看导读,再看图;点图放大、左右翻页,每张卡都有可分享的详情页。卡上每个字都出自本站正文,不列费率。
价格是个人化的
保费按年龄、性别、是否吸烟和健康状况报价,本站不列费率。持牌保险顾问可在多家公司之间比较报价(可报价的公司以其签约为准),把条款差异列在同一页上。
询价前要准备什么 →Health and insurability atlas / By insurance type
Group-to-individual conversion
Converting employer group life (sometimes health) cover to an individual policy when you leave or retire.
If you apply within the plan's window (often about a month; check your plan), you usually don't need to prove good health again — often the safest route for someone with a health history. Products, amounts and ages are limited, and pricing is at individual rates.
Outcomes possible for this type
Healthy people may compare against buying a fully underwritten individual policy.
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Converting within the plan's window usually needs no new evidence of health; products and amounts are limited — check the plan.
Basis: Two or more public underwriting guides agree
Underwriting differs by insurer; the insurer’s decision is final. General information only, not personal medical or insurance advice; condition and medication descriptions cite official sources.
