Health and insurability atlas / Health questionnaires (short forms and full set) / How insurers ask and underwrite, side by side
How insurers ask and underwrite: health questions compared
Where will the same client find it smoother? This page puts the public statements of 12 life insurers side by side across 8 topics. It uses only each insurer's public, no-login underwriting guides, application notes and FAQs; every cell carries its source and access date, and what cannot be found is marked not published, never guessed.
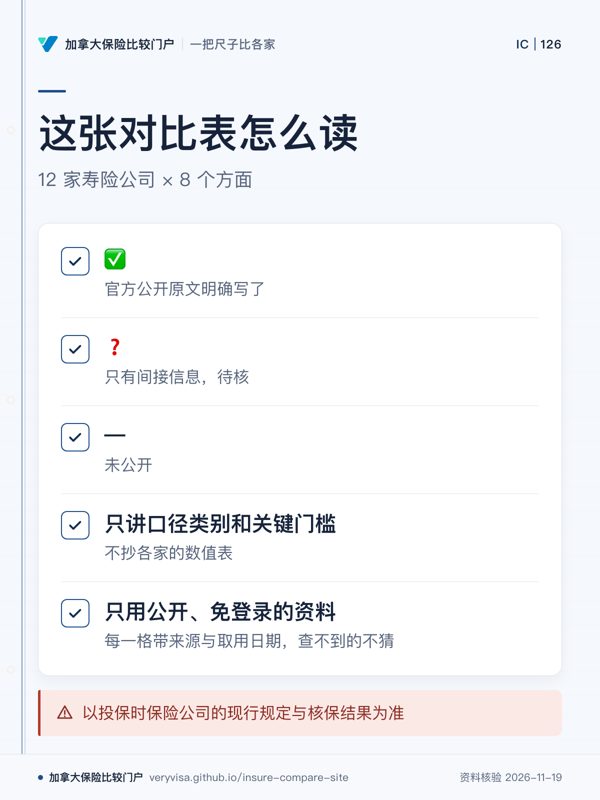
How to read: ✅ stated in an official public document; ❓ indirect only, to be verified; — not published. It describes categories and key thresholds, not the insurers' value tables; the insurer's current rules and decision at application govern.
Overview
How an advisor can use this
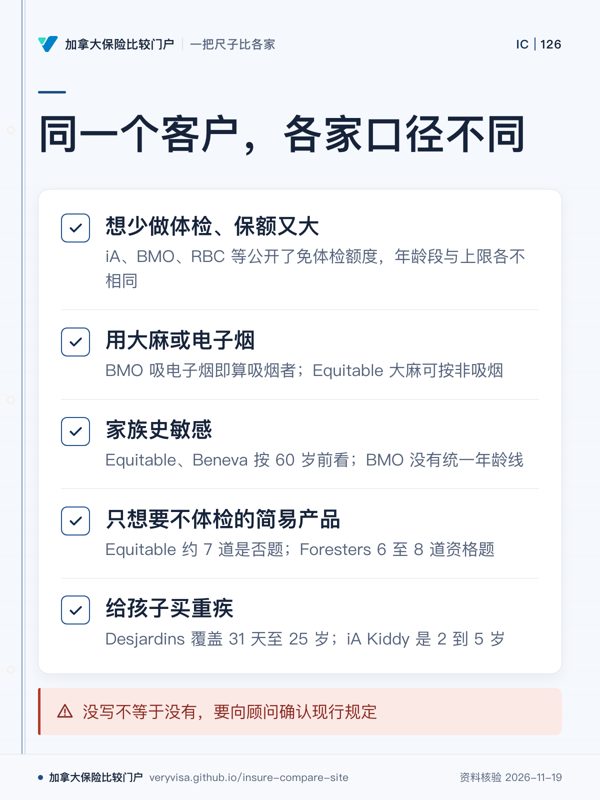
- Few exams, large amount: iA, BMO, RBC, Empire Life, Foresters and Assumption publish no-exam limits, with different age bands and caps. BMO states its accelerated underwriting excludes critical illness and people in Canada under 12 months; the others do not state such limits in public material, which does not mean there are none, so confirm current rules.
- Cannabis or vaping clients: BMO counts any vaping (even nicotine-free) as smoking while cannabis alone can rate non-smoker; Equitable says inhaled or edible cannabis can rate non-smoker; Beneva rates cannabis used with tobacco as smoking; Foresters' CI plan sets a weekly cannabis limit. The same person can land in different classes.
- Strong family history: Equitable's simplified CI declines two or more close relatives with heart disease, stroke or cancer before 60; Beneva's preferred class also looks before 60; BMO has no single age line and weighs the number of relatives and age of onset. The same history can read differently.
- Fast, no-exam simplified products: Equitable's simplified CI has about 7 yes/no questions, Foresters' simplified CI 6 to 8 eligibility questions, and Assumption prices four tiers from one questionnaire; other insurers only say a few health questions, so ask your advisor first.
- Critical illness for a child: Desjardins covers 31 days to age 25 with three child illnesses addable; iA Kiddy is a free first year for ages 2 to 5; Foresters offers a juvenile CI rider without published ages. The other insurers' public material did not show child CI ages or health questions.
By topic
Medical look-back years
How many years back the questions go for visits, tests and medicines.
- iA Financial Group Not published
Not found in public material. - Manulife Not published
Not found in public material. - Sun Life Not published
Not found in public material. - Canada Life Not published
Not found in public material. - RBC Insurance Not published
Not found in public material. - BMO Insurance ❓ To verify
The manual gives condition-specific windows (e.g. 5 years for drug use/DUI); a single application-wide lookback is not published Source (accessed 2026-11-19) - Desjardins Insurance Not published
Not found in public material. - Empire Life Not published
Not found in public material. - Equitable Life of Canada ✅ Official
Living Protection simple-issue form asks ever-had conditions plus 2-year (prior declines) and 5-year (breast/prostate, GI, alcohol/drug) windows; full underwriting lookback not published Source (accessed 2026-11-19) - Beneva ❓ To verify
Preferred-class criteria use 10-year and 5-year look-backs for drug/alcohol abuse; the general questionnaire look-back is not published. Source (accessed 2026-11-19) - Foresters Financial Not published
Not found in public material. - Assumption Life Not published
Not found in public material.
Family-history age cut-offs
At what age a parent or sibling's heart disease or cancer counts.
- iA Financial Group Not published
Not found in public material. - Manulife Not published
Not found in public material. - Sun Life Not published
Not found in public material. - Canada Life Not published
Not found in public material. - RBC Insurance Not published
Not found in public material. - BMO Insurance ✅ Official
No single age line; heart disease/cancer/diabetes weighed by number of first-degree relatives and age of onset; Parkinson's flagged if 2+ relatives with onset before 50 Source (accessed 2026-11-19) - Desjardins Insurance Not published
Not found in public material. - Empire Life Not published
Not found in public material. - Equitable Life of Canada ✅ Official
Living Protection: 2+ immediate family members with heart disease, aneurysm, stroke, PKD or cancer before age 60 disqualifies; 1024 asks onset age for breast/colon cancer etc. Source (accessed 2026-11-19) - Beneva ✅ Official
Preferred classes exclude a parent/sibling death or diagnosis of cerebrovascular disease, diabetes, cardiovascular/heart disease or cancer before age 60. Source (accessed 2026-11-19) - Foresters Financial Not published
Not found in public material. - Assumption Life Not published
Not found in public material.
Tobacco, nicotine, cannabis and vaping
How a smoker is defined and for how long.
- iA Financial Group ❓ To verify
Group-plan forms: non-smoker rates require no tobacco/nicotine (incl. cannabis mixed with tobacco) in the past 12 months; individual-policy definition not published. Source (accessed 2026-11-19) - Manulife ✅ Official
Non-smoker = no tobacco or cessation products, incl. e-cigarettes/vaporizers, in past 12 months (Doctors of BC group form; cannabis not mentioned) Source (accessed 2026-11-19) - Sun Life Not published
Not found in public material. - Canada Life Not published
Not found in public material. - RBC Insurance ✅ Official
Guaranteed Acceptance life: non-smoker rates require no tobacco use in the past 12 months. Source (accessed 2026-11-19) - BMO Insurance ✅ Official
Past 12 months of any tobacco/nicotine/vaping/hookah/small cigars = smoker; any vaping counts even without nicotine; cannabis alone or <=12 large cigars/yr can be non-smoker Source (accessed 2026-11-19) - Desjardins Insurance ❓ To verify
50+ plan form: non-smoker rates require declaring no tobacco use (incl. marijuana, nicotine patch/gum) in past 12 months; seen via search summary, PDF text unreadable. Source (accessed 2026-11-19) - Empire Life Not published
Not found in public material. - Equitable Life of Canada ✅ Official
Non-smoker = none of cigarettes, pipe, chewing tobacco, cessation products or substitutes in 12 months; up to one cigar/month with negative cotinine; cannabis (inhaled/ingested) may be Class 3 non-smoker Source (accessed 2026-11-19) - Beneva ✅ Official
Preferred classes require no tobacco in the last 60/24/12 months by class; pipe/large-cigar (>12/yr) has its own class; cannabis used with tobacco is rated as smoker. Source (accessed 2026-11-19) - Foresters Financial ❓ To verify
Public sheet only says marijuana use up to 6x/week is rated non-smoker on CI plans; tobacco/nicotine definition and look-back are not published. Source (accessed 2026-11-19) - Assumption Life Not published
Not found in public material.
Is the height-weight table public
Recorded as public or not; values are not copied.
- iA Financial Group Not published
Not found in public material. - Manulife Not published
Not found in public material. - Sun Life Not published
Not found in public material. - Canada Life Not published
Not found in public material. - RBC Insurance Not published
Not found in public material. - BMO Insurance Not published
Not found in public material. - Desjardins Insurance ✅ Official
Underwriting guide includes a height and weight chart (listed on the public page, values not shown). Source (accessed 2026-11-19) - Empire Life Not published
Not found in public material. - Equitable Life of Canada ✅ Official
The guide publishes an adult build chart in imperial and metric units Source (accessed 2026-11-19) - Beneva ✅ Official
A height/maximum-weight table is published for preferred classes; standard-class build rules are not published here. Source (accessed 2026-11-19) - Foresters Financial Not published
Not found in public material. - Assumption Life Not published
Not found in public material.
No-exam (non-medical) limits
Ages and amounts that can skip the exam.
- iA Financial Group ✅ Official
From July 2025: ages 15-50 up to $5M and ages 51-60 up to $1M need no automatic tests or vital signs; higher amounts use declaration, phone interview or paramedical exam. Source (accessed 2026-11-19) - Manulife ❓ To verify
2016 news: no-exam term limit raised from $250K to $1M for ages 18-40; current limits not verified on official public pages Source (accessed 2026-11-19) - Sun Life Not published
Not found in public material. - Canada Life Not published
Not found in public material. - RBC Insurance ✅ Official
RBC YourTerm: up to $2M and up to age 50 with no medical interview or exam (from Dec 1, 2024). Source (accessed 2026-11-19) - BMO Insurance ✅ Official
Accelerated underwriting without further medical tests: ages 18-40 up to $5M, 41-50 up to $3M, 51-60 up to $750K total life coverage Source (accessed 2026-11-19) - Desjardins Insurance Not published
Not found in public material. - Empire Life ✅ Official
Fast & Full: ages 18-40 up to $1M need only health questionnaire or tele-interview (no vitals); ages 0-17 up to $3M likewise Source (accessed 2026-11-19) - Equitable Life of Canada Not published
Not found in public material. - Beneva ✅ Official
Requirements are tiered by age and amount: lower tiers need only a declaration plus predictive analysis; higher tiers need paramedical/blood profile; age 76+ starts with a physician statement. Source (accessed 2026-11-19) - Foresters Financial ✅ Official
A-Z up to $500K no-medical; Express Elite up to $750K ($500K over age 50) for healthy clients; Live Well Plus CI no paramedical/labs up to $100K for ages up to 65. Source (accessed 2026-11-19) - Assumption Life ✅ Official
Platinum Protection whole life: $750K (18-50), $500K (51-75), $250K (76-80); Platinum Protection Term: $750K (18-50), $500K (51-75). Source (accessed 2026-11-19)
Accelerated and data-driven underwriting
Whether health-record or prescription data speeds the decision.
- iA Financial Group ❓ To verify
iA publicises instant acceptance and streamlined underwriting with a predictive-analytics FAQ, but data sources (Rx/EHR) are not specified on the page read. Source (accessed 2026-11-19) - Manulife ❓ To verify
Same article: relies on disclosures, medical records for certain conditions and in-house data analytics; heart disease/diabetes still fully underwritten (2016 info) Source (accessed 2026-11-19) - Sun Life Not published
Not found in public material. - Canada Life ❓ To verify
SimpleProtect online app has an instant-approval path with recent-meeting requirement; page does not use 'accelerated underwriting' and data sources are not stated Source (accessed 2026-11-19) - RBC Insurance ✅ Official
Instant approval notice for YourTerm; site says instant decisions for under-56, good history, term under $1M; data sources not stated. Source (accessed 2026-11-19) - BMO Insurance ✅ Official
Data-analytics based; requires tele-interview, assessed in ~2 business days, random sampling of fluid tests/APS; not for critical illness or recent immigrants (<12 months) Source (accessed 2026-11-19) - Desjardins Insurance Not published
Not found in public material. - Empire Life ✅ Official
Some applications are selected for fluid tests by random selection and predictive analytics (ages 18-50, $500K-$2M may be selected); medicals within 12 months usually accepted Source (accessed 2026-11-19) - Equitable Life of Canada Not published
Not found in public material. - Beneva ✅ Official
The public requirements chart lists predictive analysis: some tiers need only the declaration, with evidence possibly requested depending on the result; a phone interview and vital signs count as a paramedical. Source (accessed 2026-11-19) - Foresters Financial ❓ To verify
No public description of data-driven or e-record accelerated underwriting; only no-medical fast products such as Express Elite. Source (accessed 2026-11-19) - Assumption Life Not published
Not found in public material.
Simplified issue: number and shape of knock-out questions
How many questions screen out applicants on no-exam products.
- iA Financial Group ✅ Official
Access Life: simplified issue with guaranteed acceptance; a few health questions, no exam or blood test; exact question count not stated. Source (accessed 2026-11-19) - Manulife Not published
Not found in public material. - Sun Life Not published
Not found in public material. - Canada Life Not published
Not found in public material. - RBC Insurance ✅ Official
Guaranteed Acceptance: ages 40-75, $5k-$40k, no health questions, first-2-year benefit limited to premium refund; Simplified Term ages 18-55. Source (accessed 2026-11-19) - BMO Insurance ❓ To verify
Search results list insureNOW, EasyTerm and Guaranteed-Life Plus; question counts/structure not confirmed from primary text Source (accessed 2026-11-19) - Desjardins Insurance ❓ To verify
50+ permanent plan: ages 50-75, no medical exam, roughly $5k-$20k; question structure not read from primary source. Source (accessed 2026-11-19) - Empire Life ❓ To verify
Site/search show Simplified 10/20 (short health questionnaire, no exam) and Guaranteed Life Protect (ages 40-75, no health questions); question counts not read Source (accessed 2026-11-19) - Equitable Life of Canada ✅ Official
Living Protection simple-issue CI: no exam, about 7 yes/no health questions (with sub-items), MIB check, standard class only Source (accessed 2026-11-19) - Beneva ❓ To verify
Simplified and guaranteed-issue life exist with a published admissible/non-admissible condition guide; the number and structure of knock-out questions is not published. Source (accessed 2026-11-19) - Foresters Financial ✅ Official
A-Z life has no declined/postponed/rated questions; simplified CI plans use 6-8 eligibility questions; exact question structure is not published. Source (accessed 2026-11-19) - Assumption Life ✅ Official
Four simplified tiers (Platinum/Golden/Silver/Bronze) on a unified questionnaire where more NO answers earn better premiums; Platinum asks nothing on fibromyalgia, high blood pressure, thyroid, fatty liver; question count not published. Source (accessed 2026-11-19)
Child critical illness
Child critical-illness cover, ages and health questions.
- iA Financial Group ✅ Official
Kiddy plan: children aged 2-5, one-time $2,000 on first critical illness diagnosis; no health questions listed, only no prior CI diagnosis. Source (accessed 2026-11-19) - Manulife Not published
Not found in public material. - Sun Life Not published
Not found in public material. - Canada Life Not published
Not found in public material. - RBC Insurance Not published
Not found in public material. - BMO Insurance Not published
Not found in public material. - Desjardins Insurance ✅ Official
Health Priorities - Child: insured aged 31 days to 25 years; optional 3 extra children's illnesses if age 17 or younger; health questions not shown. Source (accessed 2026-11-19) - Empire Life Not published
Not found in public material. - Equitable Life of Canada Not published
Not found in public material. - Beneva Not published
Not found in public material. - Foresters Financial ✅ Official
Live Well Plus CI offers a Juvenile Critical Illness Rider; participating whole life includes a Children's Insurance Benefit with $3,000 term; juvenile ages and health questions not published. Source (accessed 2026-11-19) - Assumption Life ❓ To verify
Official page lists only a Child Insurance Benefit term-life rider on Platinum; a third party says Youth Plus (ages 15 days-17) has a limited CI benefit up to $25K, unconfirmed by Assumption text. Source (accessed 2026-11-19)
Sources by insurer
iA Financial Group
3 of 8 topics have an official public statement; 4 public documents read. Insurer page
Manulife
1 of 8 topics have an official public statement; 2 public documents read. Insurer page
Sun Life
0 of 8 topics have an official public statement; 0 public documents read. Insurer page
Canada Life
0 of 8 topics have an official public statement; 1 public documents read. Insurer page
RBC Insurance
4 of 8 topics have an official public statement; 6 public documents read. Insurer page
BMO Insurance
4 of 8 topics have an official public statement; 3 public documents read. Insurer page
Desjardins Insurance
2 of 8 topics have an official public statement; 3 public documents read. Insurer page
Empire Life
2 of 8 topics have an official public statement; 2 public documents read. Insurer page
Equitable Life of Canada
5 of 8 topics have an official public statement; 2 public documents read. Insurer page
Beneva
5 of 8 topics have an official public statement; 3 public documents read. Insurer page
Foresters Financial
3 of 8 topics have an official public statement; 2 public documents read. Insurer page
Assumption Life
2 of 8 topics have an official public statement; 3 public documents read. Insurer page
Underwriting rules change; the insurer's current documents govern. This is general information, not personal advice. To learn where you should start, give your health details to a licensed advisor for a pre-assessment.
Health questionnaires (short forms and full set) → · Medical exams and evidence →
Underwriting differs by insurer; the insurer’s decision is final. General information only, not personal medical or insurance advice; condition and medication descriptions cite official sources.