高血压
- 标准
- 加费
- 除外(通常不出现)
- 延期
- 拒保
与定期寿险评估方法相同:控制良好多为标准;读数偏高或合并其他心血管风险会加费;控制很差先延期。
依据:两份以上公开核保指南一致
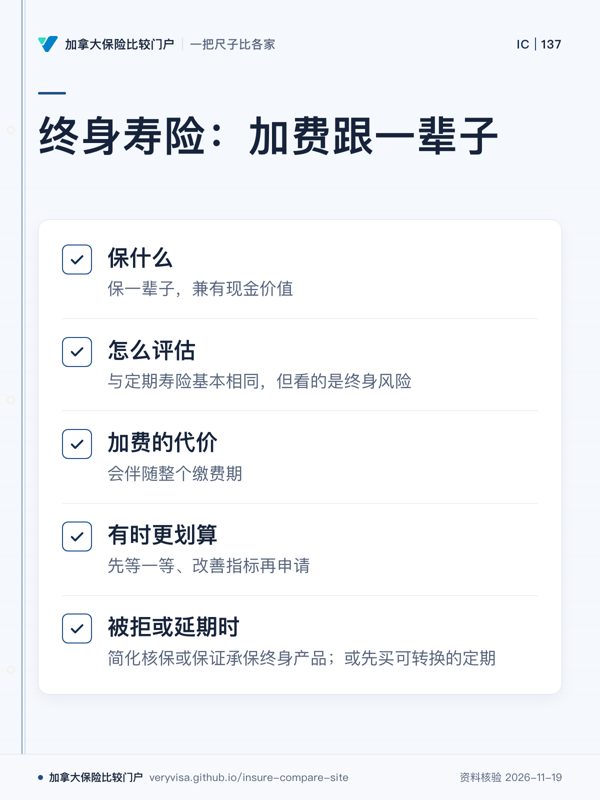
保一辈子,兼有现金价值;常用于遗产与传承。
健康评估方法与定期寿险基本相同,但看的是终身风险;加费会伴随整个缴费期,所以「先等一等、改善指标再申请」有时更划算。
这个险种可能出现的结果
同定期寿险:简化核保或保证承保终身产品;或先买可转换的定期,健康改善后再看。
与定期寿险评估方法相同:控制良好多为标准;读数偏高或合并其他心血管风险会加费;控制很差先延期。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:多数会加费;年纪较大、控制好、无并发症时有机会标准;合并心、脑、肾病多拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:通常加费,控制越好、无并发症加得越少;有严重并发症多拒保。个别公司对极好控制可标准。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:三份公开指南都没有单列;一般规律是单独的、控制好的高胆固醇多为标准,主要作为心血管风险的加分项一起看。
依据:一般规律,待核
与定期寿险评估方法相同:治疗中与结束后一段时间多为延期;之后按分期加费,年数越久加得越少;原位癌几年后可能标准。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:早期、小的乳头状癌在治疗结束一段时间后常可标准;其他类型或较晚分期等待更久或加费。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:确诊后短期内多延期;早期、治疗多年且 PSA 稳定可标准;其余按年数加费递减。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:手术或事件后一段时间多延期;之后通常加费;发病很年轻或多处病变多拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:发作后一段时间延期或拒保;之后按后遗症与年龄加费;多次发作或严重后遗症多拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:偶发、心脏结构正常可标准;持续性或合并心脏病加费;新近发现或有中风史可能延期或拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:轻中度、控制好多为标准;频繁发作、住院或吸烟加费;极重度可能拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:轻度、已戒烟可能标准或小幅加费;中重度加费;重度或仍吸烟多拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:轻度或坚持治疗多为标准;中重度未治疗加费;合并严重心肺问题可能拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:轻度、稳定多为标准;较重或反复加费;近期住院、自杀行为或正在停工多拒保或延后再议。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:肝功能正常的携带者常为标准或小幅加费;活动性感染延期;有肝硬化多拒保。
依据:两份以上公开核保指南一致
与定期寿险评估方法相同:只有一份公开指南单列:单纯脂肪肝、肝功能正常多为标准;肝功能异常或脂肪性肝炎加费;有明显纤维化可能拒保。
依据:只有一份公开核保指南
与定期寿险评估方法相同:三份公开指南都没有单列;一般规律是已排出、肾功能正常多为标准。
依据:一般规律,待核
与定期寿险评估方法相同:三份公开指南都没有单列;一般规律是确认良性多为标准,检查结果未出时通常延期到出结果。
依据:一般规律,待核
与定期寿险评估方法相同:体格表内为标准,超出越多加费越多,极端体重可能拒保;减重手术后通常先延期一段时间再按现体重评估。
依据:只有一份公开核保指南
与定期寿险评估方法相同:无并发症多为标准(部分公司要求孕晚期或产后再提交);有并发症通常延期到产后。
依据:只有一份公开核保指南
各公司核保不同,以核保结果为准。本页是一般信息,不是个人医疗或投保建议;病与药的介绍只引官方来源。
先看导读,再看图;点图放大、左右翻页,每张卡都有可分享的详情页。卡上每个字都出自本站正文,不列费率。
价格是个人化的
保费按年龄、性别、是否吸烟和健康状况报价,本站不列费率。持牌保险顾问可在多家公司之间比较报价(可报价的公司以其签约为准),把条款差异列在同一页上。
询价前要准备什么 →Health and insurability atlas / By insurance type
Permanent life (whole, participating, universal)
Lifelong cover with cash value; often used for estate and legacy planning.
Health is assessed much like term life, but over a lifetime; a rating lasts the whole premium period, so waiting until results improve can sometimes pay off.
Outcomes possible for this type
As for term: simplified- or guaranteed-issue permanent plans, or a convertible term policy first.
Assessed the same way as term life: Well controlled is usually standard; higher readings or other cardiac risks lead to a rating; very poor control is postponed.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Most are rated; older applicants with good control and no complications may get standard; with heart, stroke or kidney disease, decline is likely.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Usually rated; better control without complications means a lower rating; serious complications usually lead to decline. A few insurers may offer standard for excellent control.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: None of the three public guides lists it separately; generally, controlled high cholesterol alone is standard and is weighed together with other cardiac risks.
Basis: General pattern, to be verified
Assessed the same way as term life: Usually postponed during and for a while after treatment; then rated by stage, with the rating falling as years pass; in-situ cases may become standard after some years.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Small early papillary cancers can often be standard some time after treatment; other types or later stages wait longer or are rated.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Usually postponed shortly after diagnosis; early-stage cases treated years ago with stable PSA may be standard; others are rated, falling with time.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Usually postponed for a while after a procedure or event, then rated; very young onset or extensive disease is often declined.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Postponed or declined for a period after the event, then rated by residual effects and age; repeated events or major deficits usually decline.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Occasional episodes with a normal heart can be standard; persistent AF or heart disease is rated; newly found or with prior stroke may be postponed or declined.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Mild to moderate controlled asthma is usually standard; frequent attacks, hospital stays or smoking lead to ratings; very severe cases may be declined.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Mild cases who have quit may be standard or lightly rated; moderate to severe are rated; severe or still smoking usually decline.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Mild or well-treated cases are usually standard; untreated moderate to severe cases are rated; with serious heart or lung problems, decline is possible.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Mild, stable cases are usually standard; more severe or recurrent ones are rated; recent hospital stays, suicide attempts or current time off work usually decline or are reconsidered later.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Carriers with normal liver tests are often standard or lightly rated; active infection is postponed; cirrhosis usually declines.
Basis: Two or more public underwriting guides agree
Assessed the same way as term life: Only one public guide lists it: simple fatty liver with normal tests is usually standard; abnormal tests or steatohepatitis are rated; significant scarring may decline.
Basis: One public underwriting guide only
Assessed the same way as term life: None of the three public guides lists it; generally, passed stones with normal kidney function are standard.
Basis: General pattern, to be verified
Assessed the same way as term life: None of the three public guides lists it; generally, confirmed benign nodules are standard, and pending investigations are postponed until results are in.
Basis: General pattern, to be verified
Assessed the same way as term life: Within the build chart is standard; further above means higher ratings; extreme weight may decline. After weight-loss surgery there is usually a waiting period, then assessment at current weight.
Basis: One public underwriting guide only
Assessed the same way as term life: Uncomplicated pregnancy is usually standard (some insurers wait until late pregnancy or after delivery); with complications, postponed until after delivery.
Basis: One public underwriting guide only
Underwriting differs by insurer; the insurer’s decision is final. General information only, not personal medical or insurance advice; condition and medication descriptions cite official sources.
