高血压
- 标准
- 加费
- 除外(通常不出现)
- 延期(通常不出现)
- 拒保(通常不出现)
单纯控制良好的高血压对停工风险影响小,多数照常;合并器官损害才会加费。
依据:一般规律,待核
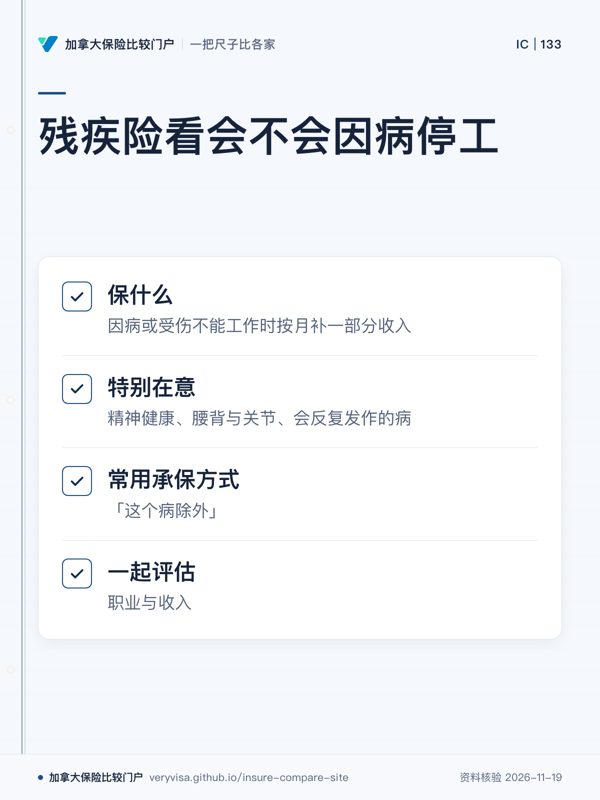
因病或受伤不能工作时按月补一部分收入。
看的是「会不会因为这个病停工」,所以对精神健康、腰背与关节、会反复发作的病特别在意,常用「这个病除外」的方式承保;职业与收入也一起评估。
这个险种可能出现的结果
团体残疾(雇主计划)通常不逐人核保;个人可考虑意外类或较短给付期的产品。
单纯控制良好的高血压对停工风险影响小,多数照常;合并器官损害才会加费。
依据:一般规律,待核
控制好、无并发症常可承保或小幅加费;有并发症时可能除外相关失能或加费。
依据:一般规律,待核
多为加费或除外;控制差或有并发症可能拒保。
依据:一般规律,待核
单独存在一般不影响残疾险。
依据:一般规律,待核
治疗期延期;之后可能除外癌症复发相关失能或加费。
依据:一般规律,待核
治疗期延期;低风险类型治愈后影响较小。
依据:一般规律,待核
治疗期延期;之后视副作用与复发风险除外或加费。
依据:一般规律,待核
多加费或除外心脏相关失能;症状限制工作时可能拒保。
依据:一般规律,待核
多延期或拒保;完全恢复多年后才可能除外承保。
依据:一般规律,待核
控制好多可承保;症状频繁影响工作时除外或加费。
依据:一般规律,待核
轻度多照常;中重度可能除外呼吸系统相关失能。
依据:一般规律,待核
多除外呼吸相关失能或加费;重度拒保。
依据:一般规律,待核
治疗良好影响小;白天嗜睡影响工作安全时会加费。
依据:一般规律,待核
残疾险最在意:常见做法是除外精神与神经类失能;近期停工多拒保。
依据:一般规律,待核
肝功能正常影响小;有肝损伤可能除外肝病相关失能。
依据:一般规律,待核
单纯脂肪肝一般不影响。
依据:一般规律,待核
反复发作者残疾险可能除外泌尿系统相关失能。
依据:一般规律,待核
良性结节一般不影响。
依据:一般规律,待核
体重高会增加腰背关节问题,可能加费或除外。
依据:一般规律,待核
一般规律:孕期申请残疾险多延期到产后。
依据:一般规律,待核
各公司核保不同,以核保结果为准。本页是一般信息,不是个人医疗或投保建议;病与药的介绍只引官方来源。
先看导读,再看图;点图放大、左右翻页,每张卡都有可分享的详情页。卡上每个字都出自本站正文,不列费率。
价格是个人化的
保费按年龄、性别、是否吸烟和健康状况报价,本站不列费率。持牌保险顾问可在多家公司之间比较报价(可报价的公司以其签约为准),把条款差异列在同一页上。
询价前要准备什么 →Health and insurability atlas / By insurance type
Disability income insurance
Replaces part of your income each month if illness or injury stops you from working.
The question is whether the condition could stop you working, so mental health, back and joint problems and recurring conditions get close attention; cover is often offered with an exclusion for that condition. Occupation and income are assessed too.
Outcomes possible for this type
Group disability through an employer is usually not individually underwritten; accident-only or shorter-benefit plans may be options.
Well-controlled hypertension alone rarely affects disability cover; organ damage leads to ratings.
Basis: General pattern, to be verified
Good control without complications is often insurable or lightly rated; complications may bring exclusions or ratings.
Basis: General pattern, to be verified
Usually rated or with exclusions; poor control or complications may be declined.
Basis: General pattern, to be verified
Generally no impact on disability cover by itself.
Basis: General pattern, to be verified
Postponed during treatment; afterwards cover may exclude cancer-related disability or be rated.
Basis: General pattern, to be verified
Postponed during treatment; low-risk types have limited impact once treated.
Basis: General pattern, to be verified
Postponed during treatment; afterwards exclusions or ratings depending on side effects and recurrence risk.
Basis: General pattern, to be verified
Usually rated or with a heart-related exclusion; may be declined if symptoms limit work.
Basis: General pattern, to be verified
Usually postponed or declined; exclusion-based cover may be possible years after full recovery.
Basis: General pattern, to be verified
Usually insurable when controlled; frequent symptoms may bring exclusions or ratings.
Basis: General pattern, to be verified
Mild is usually standard; moderate to severe may exclude respiratory-related disability.
Basis: General pattern, to be verified
Usually respiratory exclusion or rating; severe cases declined.
Basis: General pattern, to be verified
Little impact when treated; daytime sleepiness affecting work safety may lead to ratings.
Basis: General pattern, to be verified
This matters most for disability: a mental and nervous disorder exclusion is common; recent time off work usually declines.
Basis: General pattern, to be verified
Little impact with normal liver tests; liver damage may bring a liver-related exclusion.
Basis: General pattern, to be verified
Simple fatty liver generally has no impact.
Basis: General pattern, to be verified
Recurrent stones may bring a urinary-tract exclusion on disability cover.
Basis: General pattern, to be verified
Benign nodules generally have no impact.
Basis: General pattern, to be verified
Higher weight raises back and joint risks; ratings or exclusions are possible.
Basis: General pattern, to be verified
Generally, disability applications during pregnancy are postponed until after delivery.
Basis: General pattern, to be verified
Underwriting differs by insurer; the insurer’s decision is final. General information only, not personal medical or insurance advice; condition and medication descriptions cite official sources.
