中立比较 · 不替任何一家说话已收录 20 家公司

健康与投保图谱 / 按药物查

短效支气管扩张剂(急救吸入剂)

沙丁胺醇

这是什么

哮喘或慢阻肺发作时的「急救」吸入剂(蓝色喷雾)。

加拿大常见商品名(DIN 示例)

核保怎么看这个药

偶尔用影响小;用得很频繁说明控制不好,核保会问发作次数、急诊与是否需要口服激素。

对应的病

哮喘

寿险:

  • 标准
  • 加费
  • 除外(通常不出现)
  • 延期(通常不出现)
  • 拒保

重疾:

  • 标准
  • 加费
  • 除外(通常不出现)
  • 延期(通常不出现)
  • 拒保

慢阻肺(COPD)

寿险:

  • 标准
  • 加费
  • 除外(通常不出现)
  • 延期(通常不出现)
  • 拒保

重疾:

  • 标准(通常不出现)
  • 加费
  • 除外(通常不出现)
  • 延期(通常不出现)
  • 拒保

把病名、确诊日期、用药与剂量、最近检查结果带给持牌顾问,请他先做预审再正式投保。

各公司核保不同,以核保结果为准。本页是一般信息,不是个人医疗或投保建议;病与药的介绍只引官方来源。

知识卡:不看正文也能拿到这一页的核心

先看导读,再看图;点图放大、左右翻页,每张卡都有可分享的详情页。卡上每个字都出自本站正文,不列费率。
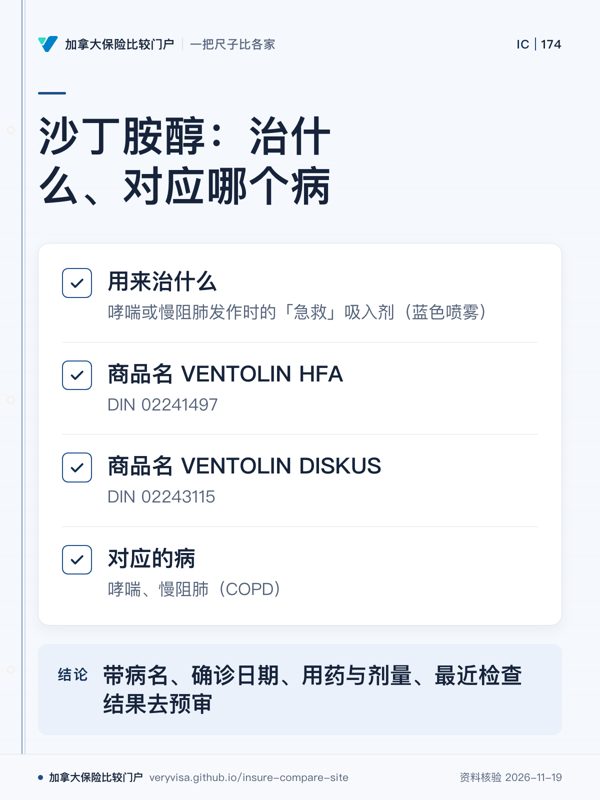
沙丁胺醇:治什么、对应哪个病;用来治什么;商品名 VENTOLIN HFA;商品名 VENTOLIN DISKUS;对应的病;带病名、确诊日期、用药与剂量、最近检查结果去预审
吃沙丁胺醇,核保会联想到哮喘
先看
先核对药盒上的商品名或 DIN 编号,确认吃的就是这一种。
易漏
核保员常先从药单看到病史,同一种药可能牵出几个病,各公司判法也不同。
下一步
点进对应的病看核保最看重什么,再去预约顾问报价。
详情与分享 →

价格是个人化的

带着这 3 个问题请顾问比较报价

  1. 我家最大的风险是收入中断、生病还是养老钱不够?该先配哪一类?
  2. 同样的预算,几家公司的报价和条款差在哪里?
  3. 我现有的保单保额够不够、受益人写对了没有?

保费按年龄、性别、是否吸烟和健康状况报价,本站不列费率。持牌保险顾问可在多家公司之间比较报价(可报价的公司以其签约为准),把条款差异列在同一页上。

询价前要准备什么 →
微信联系持牌保险顾问持牌保险顾问的微信二维码:手机上长按识别,电脑上用手机扫码

持牌保险顾问可在多家公司之间比较报价(以其签约公司为准)。请勿通过微信发送 SIN 或密码。

Health and insurability atlas / By medication

Short-acting bronchodilator (reliever inhaler)

Salbutamol

What it is

The 'reliever' inhaler (often blue) for asthma or COPD symptoms.

Common Canadian brands (example DIN)

How underwriters read this medication

Occasional use has little impact; frequent use suggests poor control, so underwriters ask about attacks, ER visits and oral steroids.

❓ To verifyStrength of basis: General pattern, to be verified

Conditions it treats

Asthma

Life:

  • Standard
  • Rated (extra premium)
  • Exclusion (not typical)
  • Postponed (not typical)
  • Declined

Critical illness:

  • Standard
  • Rated (extra premium)
  • Exclusion (not typical)
  • Postponed (not typical)
  • Declined

COPD (chronic obstructive pulmonary disease)

Life:

  • Standard
  • Rated (extra premium)
  • Exclusion (not typical)
  • Postponed (not typical)
  • Declined

Critical illness:

  • Standard (not typical)
  • Rated (extra premium)
  • Exclusion (not typical)
  • Postponed (not typical)
  • Declined

Bring the condition, diagnosis date, medications and doses, and recent test results to a licensed advisor and ask for a pre-assessment before a formal application.

Underwriting differs by insurer; the insurer’s decision is final. General information only, not personal medical or insurance advice; condition and medication descriptions cite official sources.
