Health and insurability atlas / Medical exams and evidence
Medical exams and evidence
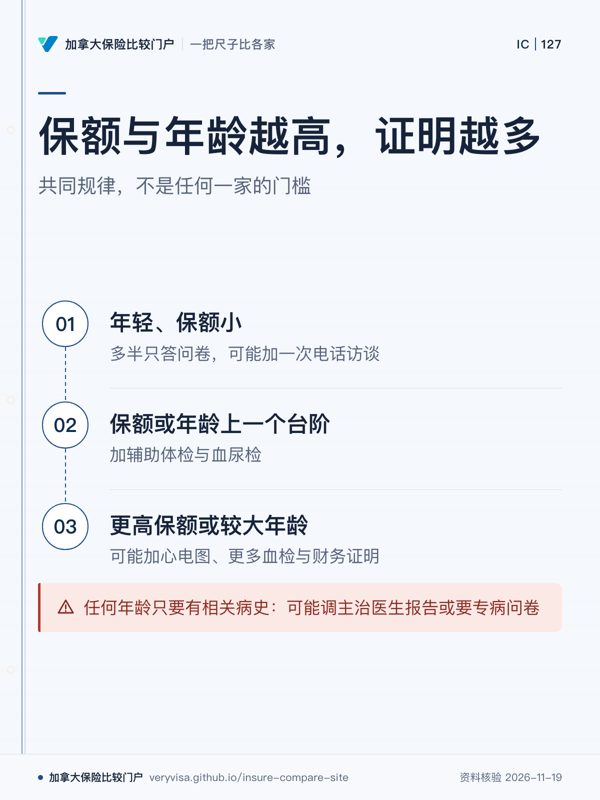
The larger the amount and the older the applicant, the more evidence of health an insurer asks for. These 'age and amount requirements' differ by insurer; below are the common patterns, not any company's actual thresholds.
Common patterns
- Young applicants, smaller amounts: often questions only, perhaps a tele-interview.
- Larger amounts or older ages: paramedical plus blood and urine tests.
- Larger still, or older still: ECG, more blood work and financial evidence may be added.
- At any age, a relevant health history can bring an APS or a condition questionnaire.
What each item is
- Health questionnaire
- Health questions on the application; answer truthfully — inaccurate answers can void the policy or lead to a denied claim.
- Tele-interview
- A nurse or underwriter reviews health and lifestyle by phone.
- Paramedical exam
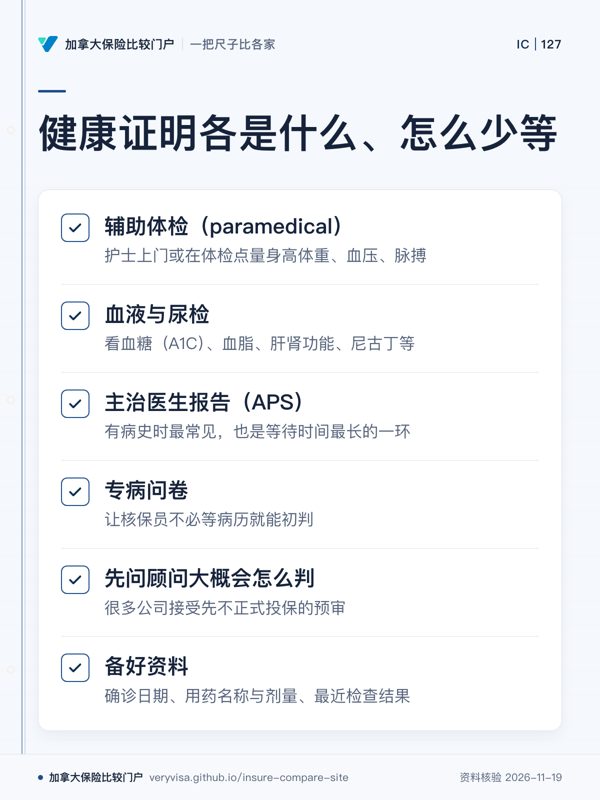
- A nurse measures height, weight, blood pressure and pulse at home or a clinic and records history.
- Blood and urine tests
- Checks blood sugar (A1C), cholesterol, liver and kidney function, nicotine and more.
- ECG
- Common at older ages or larger amounts; more cardiac tests if there is heart history.
- Attending physician statement (APS)
- With your consent the insurer requests records from your doctor; most common with a health history and often the slowest step.
- Condition-specific questionnaire
- Such as respiratory, mental health or diabetes questionnaires, helping a tentative decision before records arrive.
- Financial evidence
- For large amounts, proof that the amount fits income and assets.
Ways to save weeks
- Ask your advisor for a likely decision first — many insurers accept an informal trial or pre-assessment.
- Having diagnosis dates, medication names and doses and recent results ready shortens the wait.
Health questionnaires (short forms and full set) →
Underwriting differs by insurer; the insurer’s decision is final. General information only, not personal medical or insurance advice; condition and medication descriptions cite official sources.