🃏 Flashcards · 3 闪卡 · 3 张 🖼 Slides · 2 幻灯 · 2 页 ✍️ Questions · 7 刷题 · 7 道
分离基金与年金 Segregated Funds & Annuities P2 稳住 P2 Hold steady
ZH EN ZH + EN
先看这一章怎么考 First, how this chapter is tested
区分“合同写死/法律强制的保证条款”与“保险公司自定的行政规则”:题干给出免费转换次数、重置年龄上限或不可撤销受益人变更条件,要求判断哪一项属于法定或合同保证、哪一项因保险人而异。 Distinguishing contractually fixed or statutory guarantees from insurer administrative rules: Scenarios present conditions such as annual free switch limits, reset age ceilings, or irrevocable beneficiary changes, requiring candidates to determine which provisions are legally binding guarantees versus insurer-discretionary rules. 注册账户与非注册账户的结构性限制:给出客户希望指定候补受保人(contingent annuitant)或将分离基金合同用于银行贷款抵押的场景,测试是否掌握只有非注册合同才允许三方分离、转让及设候补受保人。 Structural limitations of registered versus non-registered contracts: Presenting scenarios where a client wishes to designate a contingent annuitant or pledge a segregated fund contract as bank collateral, testing whether candidates know that only non-registered contracts permit role separation, collateral assignment, and contingent annuitants. 转换(switch)与重置(reset)的叠加后果:以非注册合同的免手续费转换为切入点,同步考察资本利得税务处置(按 50% 计入率)以及触发到期重置后到期日重新顺延 10 年的连锁影响。 Compounding consequences of switches and resets: Using fee-free switches in non-registered contracts as an entry point to evaluate capital gains tax dispositions (at a 50% inclusion rate) alongside the ripple effect of a 10-year maturity date extension triggered by a maturity reset. 最常丢分的陷阱(看到题干信号就警觉) Traps that cost the most marks (watch for the signal in the stem)
免费Switch零后果陷阱 The zero-consequence free switch trap 题干出现 non-registered contract、free switch、market value 高于原投入或 switch triggering a reset 等字眼。 The question stem mentions a non-registered contract, free switch, market value exceeding original deposit, or a switch triggering a reset. 在世失能误走身故理赔陷阱 Mistaking lifetime incapacity for a death claim trap 题干同时出现 contract maturing soon、incapacitated owner/annuitant、Power of Attorney (POA) 以及 named beneficiary。 The question stem mentions contract maturing soon, incapacitated owner/annuitant, Power of Attorney (POA), and a named beneficiary. 注册合同设候补受保人陷阱 Naming a contingent annuitant on a registered contract trap 题干出现 RRSP、RRIF 或 LIRA 等注册分离基金合同,并询问能否添加 contingent annuitant 或将合同质押(collateral)。 The question stem presents a registered segregated fund contract such as an RRSP, RRIF, or LIRA and asks about adding a contingent annuitant or pledging the contract as collateral. 本章考点页:导图、要点表、7 道带逐项解析的练习 →
上一篇讲清楚了分离基金为什么能有保证;这一篇要回答的是另一个问题:拿到一份真实合同,哪一条是保险公司必须兑现的,哪一条是保险公司自己定的、每家公司都不一样。 这正是考纲把"落实推荐方案"与"保障期内服务"分开考的原因——柜台工作的大部分错误不是算错保证金额,是把"合同条款"和"保险公司自定的行政规则"混为一谈。读完这一篇,你要能做三件事:逐项区分一份 IVIC 合同与一份年金合同里哪些条款写死、哪些可协商;讲清楚到期理赔与身故理赔为什么走两条不同的手续;以及说清楚 BC 在这一章里的两处特例——分别核 DSC 的市场行为依据与 POA 的具体授权边界。
一、制度设计与底层逻辑:合同条款回归哪部法律 本节回答 This section answers 回答合同条款归哪部法管、哪些写死不可改及犹豫期如何退款 Governing statutes for contract terms, immutable clauses, and rescission refund mechanics 本章考题 1 Question 1 本章考题 2 Question 2
分离基金(IVIC)的三方角色——持有人、受保人、受益人——以及保证机制的法理基础,分离基金:保证、保护与它和共同基金的真正区别 已经讲过,这里不重复。这一篇要往下一层:这份合同的具体条款,法律上受谁约束?
答案分两半,且两半分工不同:合同条款本身 ——谁能当受益人、受益人可撤销还是不可撤销、受益人先于受保人身故怎么办、保险公司在什么条件下可以免责付款——回归的是 BC《Insurance Act》第三部分(人寿保险)。这部法律不是分离基金专属的,它和普通寿险合同同源,因为分离基金在法律上就是一份保险合同。几条与本章关系最密切的条文:受益人指定的一般规则、不可撤销受益人未经其本人同意不得变更、受益人先于受保人身故时份额如何在生存受益人间分配、指定合格受益人后保险金免受持有人债权人追索、以及保险公司在收到影响权益的文件前依现有记录付款即可免责。这几条不是分离基金专属条款,是整个人寿保险合同法律体系的地基,IVIC 只是站在这块地基上加了一层"市值浮动的保险赔付"。
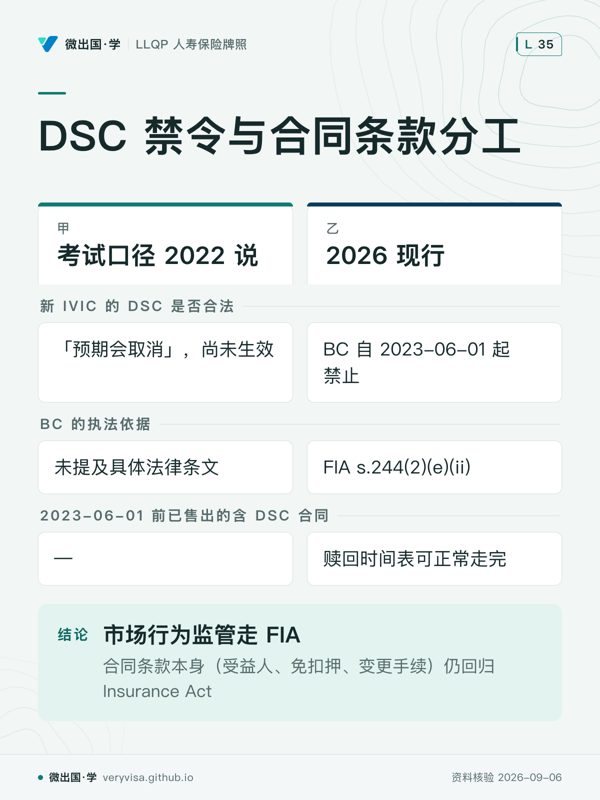
但市场行为监管走的是另一部法律。 分离基金 DSC(递延销售费)禁令用的执法工具是《Financial Institutions Act》(FIA),不是《Insurance Act》——seg-ch02-segregated-funds 已详细展开这条分野,本篇第二节会用一张三列表简要复核,因为它直接决定了下面"合同变更"一节该往哪本法里找答案。
申请环节的两项投资者义务与一处例外。 投资者要做两件事:如实提供信息、按约出资。申请表通常要求持有人本人签字,其中一种代签情形是持有人由有效财产授权书(Power of Attorney for property,POA)代理人代表——此时代理人可以代签申请表,但是否有权代为指定受益人,考试口径明确提示需要另外寻求法律意见,不能想当然认为"能签申请表就能指定受益人"。
注册与非注册的结构性差异,决定了合同里哪些角色可以分开。 注册账户(RRSP/RRIF/LIRA 等)强制要求持有人与受保人是同一人,不可转让、不可用作抵押;非注册账户则允许持有人与受保人分离,且本节个人 IVIC 的候补受保人选项依非注册合同办理;RRIF/TFSA 的配偶继任安排须另按账户及合同确认——在初始受保人生前指定,待其身故后依合同由另一人接替,合同延续至最后一位在世受保人身故才触发死亡给付。这条规则的直接后果是:注册合同一旦指定受保人就不能更改,也没有候补受保人这个选项,因为持有人=受保人是强制绑定的,改受保人等于改持有人,那是另一套完全不同的手续。
年金合同与 IVIC 都须核法律及合同,但流动性不同。传统固定给付年金通常一经购买便难以更换类型或退回本金;FCAC 也明确提示合同可能提供冷静期或起付后的付费取消权。因此应说明该份合同是否允许撤销或部分变现,不能宣布所有年金除受益人外一律不能改。积累年金的到期、续期、转换或提前提款条件另看合同,市场价值调整也并非每份合同必然扣款。
一张表说清楚:IVIC 合同十项条款,逐条对照
一张表说清楚:年金合同六项条款,逐条对照
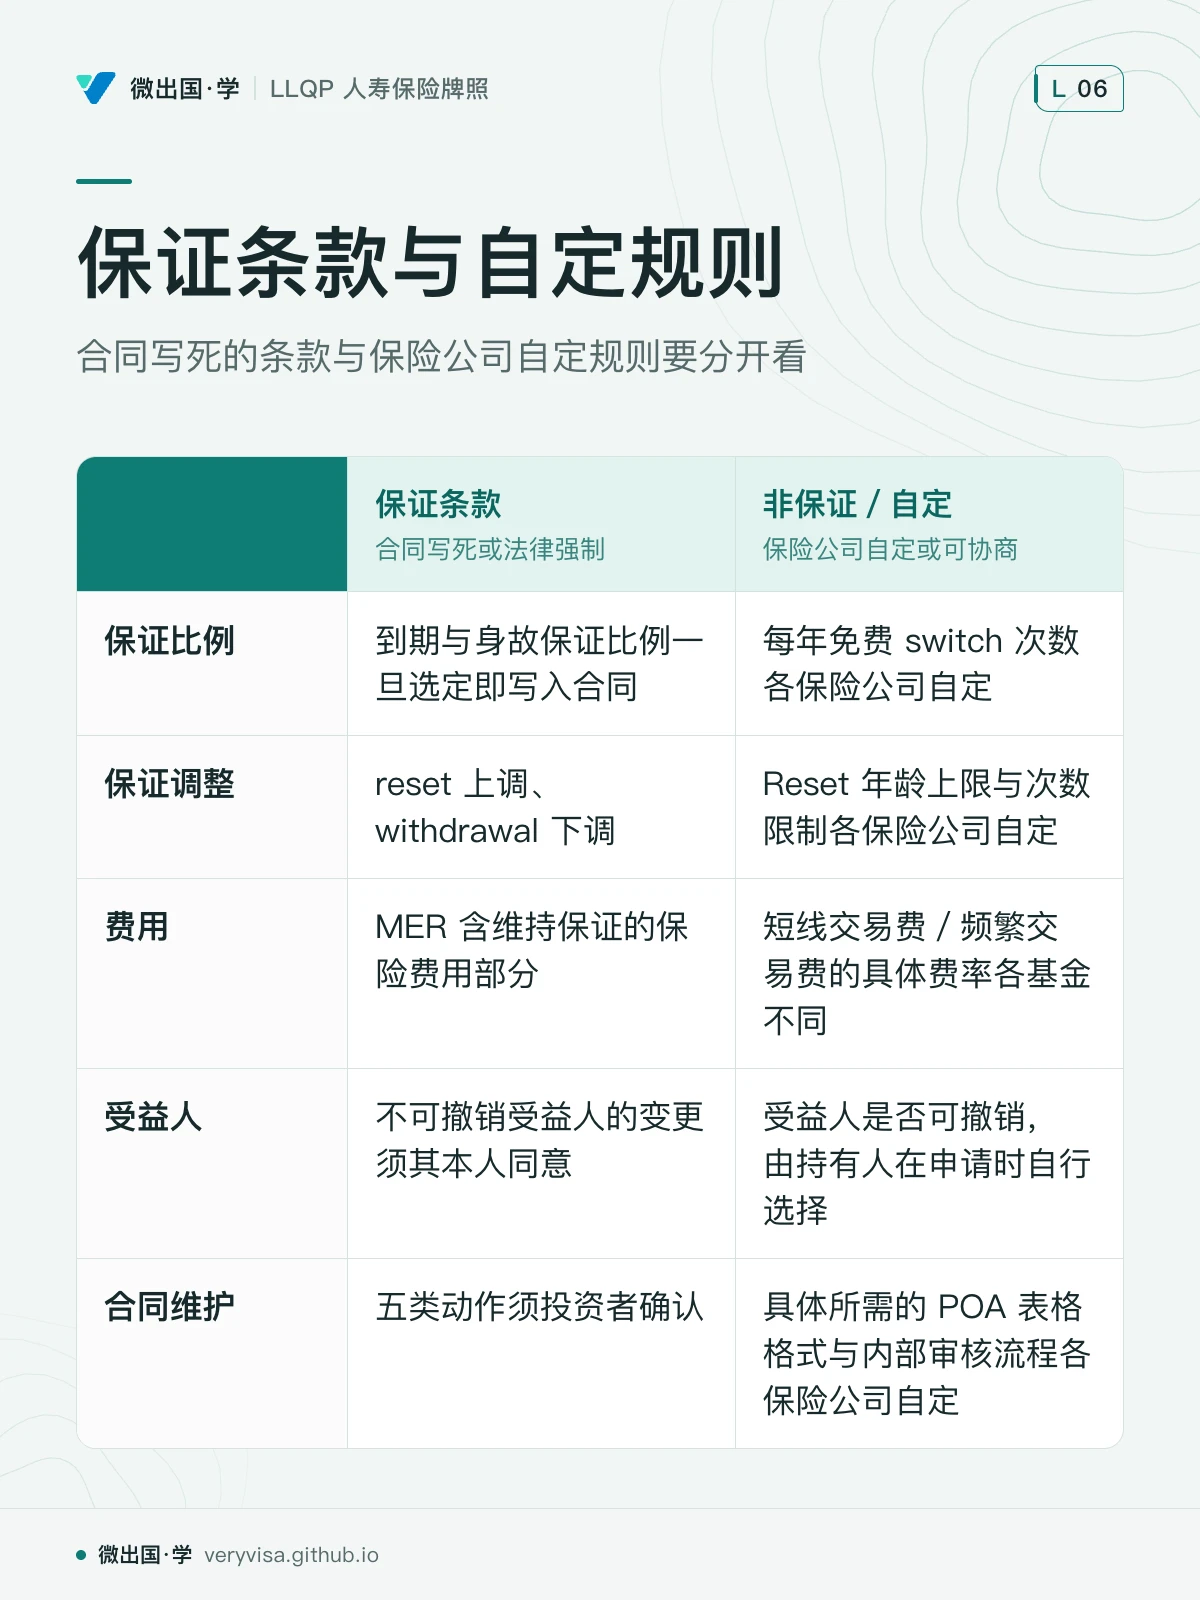
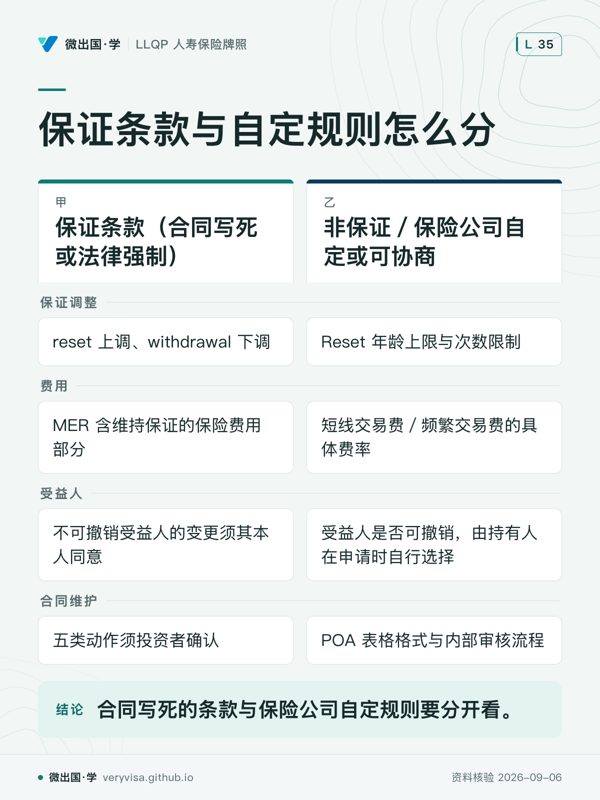
两栏对照:哪些是保证条款,哪些是保险公司自定的行政规则
图:保证条款与自定规则——合同写死的条款与保险公司自定规则要分开看
✕
"合同变更"必须书面且由保险公司制作,口头约定一律无效
年金合同的批注/附加条款(amendment/addendum)——用来豁免某条款或更正错漏——必须由保险公司书面制作并由投保人签字才生效 。代理人与客户口头达成的任何"特殊安排",只要没有落到这份书面批注上,在法律上等于不存在。这条纪律同样适用于 IVIC 合同的日常维护:受益人变更、地址变更等都要求书面通知保险公司,受益人文书须符合法定形式,地址等行政变更则按保险人处理规则,不宜共用一个“签字即生效”的答案。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
Marcus invested $50,000 into a non-registered segregated fund contract. He received the written confirmation by courier on Tuesday and immediately decided to cancel the contract the next business day after a sudden market drop reduced the fund's market value to $48,200 on the valuation day following his rescission request. How much will Marcus receive upon exercising his right of rescission?
Marcus 在一份非注册分离基金合同中投入了 $50,000。他在周二通过快递实际收到书面确认书,并在次一营业日因市场突然下跌而决定撤回合同;在他提出撤回请求后的次一估值日,该基金市值降至 $48,200。Marcus 行使犹豫期解约权后能拿回多少金额?
a $50,000, because the right of rescission guarantees a full refund of the original principal deposited. ✗ 错误。落入“犹豫期全额退本金”陷阱。分离基金的犹豫期解约权(right of rescission)并不保证退还全部原始本金,而是退还已投入金额与撤回请求次一估值日基金市值两者中的较低者。 Incorrect. Falls into the full refund of principal during rescission trap. The right of rescission for a segregated fund does not guarantee a full refund of the original deposit; rather, it refunds the lesser of the amount invested and the fund's market value on the valuation day following the rescission request.
b $48,200, because the refund equals the lesser of the amount invested and the fund value on the valuation day following the rescission request. ✓ 正确。在从实际收到确认书或邮寄后第 5 个营业日较早者起算的 2 个营业日内书面撤回合同时,退款金额等于已投入金额($50,000)与撤回请求次一估值日基金价值($48,200)两者中的较低者(lesser of the two)。 Correct. When rescinding the contract in writing within two business days from the earlier of actual receipt of confirmation or five business days after mailing, the refund equals the lesser of the amount invested ($50,000) and the fund market value on the valuation day following the rescission request ($48,200).
c $37,500, because early cancellation before the 10-year maturity date limits the payout to the minimum 75% maturity guarantee. ✗ 错误。混淆了犹豫期解约权与 10 年到期保证(maturity guarantee)。75% 到期保证仅在合同满 10 年到期且市值低于保证额时适用,犹豫期撤回按投入本金与次一估值日市值的较低者结算。 Incorrect. Confuses the right of rescission with the 10-year maturity guarantee. The 75% maturity guarantee applies only when the contract reaches its 10-year maturity date and market value is below the guaranteed amount, whereas rescission refunds are calculated as the lesser of deposit and market value on the subsequent valuation day.
d $47,236, because a mandatory 2% short-term trading fee is deducted from the market value upon any withdrawal within 90 days. ✗ 错误。混淆了犹豫期撤回(right of rescission)与日常 90 天内短线转换或赎回(short-term trading fee)。在法定 2 个营业日犹豫期内合法撤回合同按本金与次一估值日市值的较低者退款,不额外叠扣 2% 短线交易费。 Incorrect. Confuses a rescission withdrawal with standard short-term trading fees charged within 90 days of deposit. Rescinding the contract within the statutory two-business-day cooling-off period refunds the lesser of principal and subsequent valuation day market value without deducting an additional 2% short-term trading fee.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :b
二、2026 现行政策与数字:考试口径写的和现在不一样的地方 本节回答 This section answers 回答DSC禁令双口径与总成本报告新规对分离基金年报的要求 Dual benchmarks for the DSC ban and Total Cost Reporting requirements for annual statements
考场与现行对照表:分离基金 DSC 禁令的法律依据(分离基金专章已详细展开,这里只看与合同条款相关的一句)
总成本披露(TCR)对合同年度对账单的影响——分离基金合同明确在覆盖范围内(原文已核实)
2026 年起生效的 CSA/CCIR/CISRO/CIRO 联合总成本报告新规(TCR)要求投资产品年度对账单同时用百分比与实付加元两种口径披露费用,2027 年初投资者首次收到新格式报告。分离基金合同(IVIC)已被 CSA/CCIR 2023-04-20 联合指引明确纳入 TCR 覆盖范围 ,并要求在保证成本未计入其他费用时,对共同基金没有的"保证成本合计($)"一项上单独披露(CSA(加拿大证券管理局)与 CCIR(加拿大保险监管者… 原文已核;BC 2025-12-10 采纳全国整合指引,Insurance Council of British…(论坛解读) )。本次证据确认的是 IVIC;不能仅凭指引名称推断所有年金合同均被排除,其他年金产品的披露要求须另按产品及适用规则核对。柜台遇到客户问"我的分离基金合同年报格式会不会变",可以肯定地答"会,2027 年初起按新格式披露"。
长青不变的部分
撤回权的时钟、重置或提款的保证调整、到期与身故证明要求都须回合同及适用法律。本页所引 iA/Manulife 合同采用“实际收到确认与邮寄后第 5 个营业日两者较早者,再加 2 个营业日”的撤回窗口;不能把这些数字当作无需来源的永久通则。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
Clara holds an individual variable insurance contract (IVIC) in British Columbia and asks her advisor how the Total Cost Reporting (TCR) rules will change her annual statement starting in early 2027. Which explanation accurately reflects the verified rule?
Clara 在 BC 省持有一份个人可变保险合同(IVIC),她向代理人询问总成本报告(TCR)新规自 2027 年初起将如何改变她的年度对账单。下列哪项解释准确反映了经核实的规则?
a Her annual statement will disclose costs in both percentages and actual dollar amounts, including a separate dollar figure for total insurance guarantee costs if not already embedded in other reported fees. ✓ 正确。总成本披露(Total Cost Reporting, TCR)新规明确将分离基金合同(IVIC)纳入覆盖范围,要求自 2027 年初起在年度对账单中同时用百分比与实付加元两种口径披露费用,且在保证成本未计入其他费用时须单独披露“保证成本合计($)”。 Correct. Total Cost Reporting (TCR) rules explicitly include Individual Variable Insurance Contracts (IVICs), mandating that annual statements disclose fees in both percentages and actual dollar amounts starting early 2027, along with a separate dollar figure for total insurance guarantee costs if not already embedded in other reported fees.
b Her annual statement format will remain unchanged because insurance contracts are governed by provincial insurance legislation and are completely exempt from securities-style cost reporting. ✗ 错误。误以为分离基金作为保险合同可豁免总成本披露。CSA/CCIR/CISRO/CIRO 联合指引及 BC 省采纳的规则已明确将 IVIC 纳入 TCR 覆盖范围,2027 年初起必须按新格式披露。 Incorrect. Mistakenly assumes segregated funds are exempt from total cost reporting as insurance contracts. Joint guidance from CSA/CCIR/CISRO/CIRO and rules adopted in British Columbia explicitly bring IVICs under TCR scope, requiring the new disclosure format starting early 2027.
c Her annual statement will only report the management expense ratio (MER) as a percentage, while retroactively cancelling any remaining deferred sales charge (DSC) schedule on pre-2023 deposits. ✗ 错误。包含两处错误:一是 TCR 要求同时用百分比与实付加元披露而非仅列百分比;二是 2023-06-01 前售出的旧 DSC 合同赎回时间表可正常走完,并未被统一清零。 Incorrect. Contains two errors: first, TCR mandates reporting in both percentages and actual dollars rather than percentages alone; second, redemption schedules on legacy DSC contracts sold before June 1, 2023 run their course normally rather than being retroactively eliminated.
d Her annual statement will replace all fund-level fee disclosures with a single flat administration fee prescribed uniformly by the provincial regulator. ✗ 错误。各基金的 MER 与保险费用具体比例属于各基金和保险公司自定事项,监管机构通过 TCR 强制的是“百分比+加元金额及保证成本”的透明披露格式,而非统一规定单一固定费率。 Incorrect. Specific MERs and insurance guarantee fees are established at the discretion of individual funds and insurers; TCR regulations mandate transparent disclosure in percentages, dollar amounts, and guarantee costs rather than imposing a single uniform administrative fee.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :a
三、实务流程:从申请到理赔,谁在哪一步做什么 本节回答 This section answers 回答申请交付、转换重置、10年到期三选一及理赔与核实流程 Application delivery, switch and reset mechanics, 10-year maturity options, and claims procedures 本章考题 3 Question 3 本章考题 4 Question 4
申请与交付阶段。 考试口径示范专人或挂号邮寄交付;现行合同也可能依法约定电子交付,须留有效同意及交付证据,随附信息文件夹(information folder)、Fund Facts 与合同确认书;若交付材料含回执,回执须完成签署并有见证人签字后寄回保险公司。完成购买、switch、reset、提款、终止合同这五类动作,保险公司都必须取得投资者的确认,口头指示与书面指示同样具有约束力——这条前篇已经提过,这里补一句实务细节:确认不是销售环节的终点,代理人在合同存续期间的持续服务义务(监控客户处境变化、监控产品、年度回顾)才刚开始。
转换(switch)与重置(reset)的操作细节。 Switch 分排期式(scheduled,通常年末自动执行、免手续费,但保险公司可取消或改派)与临时式(unscheduled,随时可申请)。每家保险公司每年提供若干次免费 switch,超出后可能收提款手续费;若在购买后 90 天内进行 switch,可能被收短线交易费(考试口径举例 2%)或干脆不被允许——2026 年真实市场的 Fund Facts 文件证实了这条机制仍然有效(下一节"2026 市场"会给出具体数字)。非注册合同的 switch 通常构成税务处置;注册合同内部转换不逐次申报资本利得;非注册合同的转换视为处置,超过调整成本基础的部分要计入当年资本利得,与是否收手续费无关。Reset 同样分排期式、临时式、自动式三种,须区分到期保证重置与仅身故保证重置;只有合同规定重订到期日时才延长,例如假设 10 年到期重置重新等 10 年,保险公司通常对 reset 设年龄上限(考试口径举例 80 岁),原因是过了这个年龄段的死亡率陡增,保险公司大概率要补足身故保证与市值的差额。Switch 也可能同时触发 reset,第六节案例一会完整演示这个组合后果。
10 年到期时的三选一。 到期时合同价值可选择现金领取、购买年金、或续保进入新保证期;续保的初始投入 = 市值与保证金额两者取高者(若市值低于保证,按保证值续保),死亡给付保证延续。
理赔阶段:到期理赔与身故理赔走两条不同的手续。 到期理赔由持有人本人或其 POA 代理人申请,不需要提供死亡证明——这是自动结算的契约义务,到期日一到即完成,不要求投资者主动申请才能拿到保证补足款。身故理赔由受益人或遗产代表(executor/administrator,魁北克称 liquidator)申报,需提供合同号、申报人签字、代理人姓名与编号、死亡证明或主治医生证明(Attending Physician's Statement),保险人可要求死亡证书等资料,是否须原件按其合法证明要求判断;若死亡发生在境外可能需要额外文件。两类理赔的保证金额计算逻辑相同:保证=存款的约定百分比,因 reset 上调、因 withdrawal 下调,市值与保证取高者支付。
POA 在理赔中的权限边界。 代理人须核授权书效力、范围、合同及是否符合本人的利益;不得将任何来件一律当作本人有效指令。考试口径 AMF 9e 2022 提到 BC 受益人例外,现行规则是:BC《Power of Attorney Act》s.20 对持续授权代理人作出限定:变更本人已有受益人指定须法院授权;更新、替换或转换类似文书时,可依条件沿用本人有能力时指定的同一受益人;另建文书时的新指定限本人遗产。代签申请表不等于可任意换受益人。
年金合同的专属实务 :FINTRAC 对完全由合资格养老金直接转入、完全由团体寿险赔款购买、注册年金等列有分别适用的身份核实例外;不能省略“完全”“直接”或把它解释为豁免可疑交易义务,大额现金与虚拟货币另核。年龄证明仍是合同事项。身故给付须看保证期、退款选项与联合结构,锁定养老金还可能有配偶优先权及豁免文件。累积型年金提前退保是否收 MVA、如何计算正负调整,依合同及利率条件判断,不能只凭“提前”二字断定一律扣款。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
Ten years ago, Evelyn deposited $100,000 into a segregated fund contract carrying a 75% maturity guarantee; she made no withdrawals or resets. Today the contract reaches its maturity date with a market value of $68,000, and Evelyn elects to renew it into a new guarantee period. What is the initial investment value recorded for her renewed contract?
十年前,Evelyn 在一份附 75% 到期保证的分离基金合同中存入 $100,000,期间未做过任何提款或重置。今天合同到期,市值为 $68,000,Evelyn 选择将合同续保进入新的保证期。她续保合同的初始投入价值是多少?
a $68,000, because contract renewals must always start at the current market value unless the investor takes the payout in cash. ✗ 错误。落入“只有领现才能享受到期保证补足”的陷阱。10 年到期选择续保进入新保证期时,续保的初始投入等于市值与到期保证金额两者中的较高者,若市值低于保证,直接按保证值续保。 Incorrect. Falls into the trap of believing guarantee top-ups apply only to cash surrenders. When electing contract renewal for a new guarantee period at 10-year maturity, the starting deposit equals the higher of market value and maturity guarantee, renewing directly at the guaranteed amount if market value is lower.
b $100,000, because renewing a contract at maturity automatically restores the full original deposit as the new starting balance. ✗ 错误。混淆了 75% 到期保证(maturity guarantee)与 100% 本金。该合同约定的是 75% 到期保证(即 $75,000),而非 100% 保证,因此保险公司补足至 $75,000 而非 $100,000。 Incorrect. Confuses a 75% maturity guarantee with a 100% principal guarantee. The contract specifies a 75% maturity guarantee (equal to $75,000) rather than a 100% guarantee, so the insurer tops up the balance to $75,000 rather than $100,000.
c $75,000, because upon renewal at maturity the initial investment of the new guarantee period equals the greater of the market value and the maturity guarantee amount. ✓ 正确。10 年到期时客户可在领现、买年金或续保进入新保证期之间三选一;若选择续保(renewal),续保的初始投入等于到期市值($68,000)与到期保证金额($100,000 × 75% = $75,000)两者中的较高者,且身故给付保证延续。 Correct. At 10-year maturity, the client can choose between cash payout, annuity purchase, or renewal into a new guarantee term; if renewal is elected, the starting balance equals the higher of the maturity market value ($68,000) and the maturity guarantee ($100,000 x 75% = $75,000), and death benefit guarantees continue.
d $71,500, because the insurer splits the shortfall between the $75,000 maturity guarantee and the $68,000 market value equally when a policy is renewed. ✗ 错误。合同中不存在“平摊差额”的规则。到期保证是写死在合同中的契约义务,只要到期市值低于保证值,即按全额到期保证值($75,000)作为续保初始投入。 Incorrect. No rule exists to split the difference evenly. The maturity guarantee is a binding contractual obligation, meaning that whenever maturity market value falls below the guarantee, the full guaranteed amount ($75,000) serves as the renewal starting balance.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :c
四、2026 市场:读一份真实 Information Folder 的顺序 本节回答 This section answers 回答如何按标准顺序读信息文件夹及区分法律发行方与品牌名 Standard order for reading an Information Folder and distinguishing legal issuers from brand names
这一节回源核实了三家全国性保险公司当前在售的分离基金产品线,全部来自各自官网 2023–2026 年发布的现行 Information Folder 与 Fund Facts 原件,不是二手转述:
Manulife(The Manufacturers Life Insurance Company)· GIF Select :保证档位分 InvestmentPlus 75/75 与 75/100 两级,它对应的正是本课反复讲的"到期保证/身故保证可以不对称"这个概念。2026 年官方 Fund Facts 显示,90 天内提前赎回或转换收取 2% 的短线交易费(Early Withdrawal Fee)、年内 switch 超过 5 次收 2% 频繁交易费——这与考试口径"90 天内 switch 可能收短线交易费,举例 2%"完全吻合,是目前唯一找到的"现行费率与考试口径举例数字一致"的实证;犹豫期解约权仍是 2 个营业日,和本篇第三节讲的合同长青规则一致。iA Financial Group(Industrial Alliance Insurance and Financial Services Inc.)· IAG Savings and Retirement Plan :这是三家里唯一在官方 Information Folder 里完整列出四级保证档位的产品——Classic Series 75/75、Series 75/100、Ecoflex Series 100/100,外加一个收入型的 FORLIFE Series(分 Savings Stage 与 Income Stage 两阶段)。它对应的正是本课"保证档位可以不止两级、且部分合同还提供收入型附加保证(GLWB/GMWB 概念的实际产品化)"这个知识点。犹豫期条款与退款计算方式(已投入金额与当日基金价值两者较低者)与考试口径完全一致。Canada Life(The Canada Life Assurance Company)· 分离基金(Standard series / Preferred series 1 / Partner series / Preferred partner series / Constellation series) :这是三家里版次最新的一份(2026 年 4 月认证),也是唯一把"哪个保证档位能重置哪一项"讲清楚的官方件——75/75 档不提供重置;75/100 档只能重置身故保证;100/100 档身故与到期保证都能重置。这条细节考试口径笔记只笼统写"部分合同提供重置",这份现行官方件把它具体化了,也印证了本课反复强调的"75/75、75/100、100/100 是行业通用三档"这个结论——三家公司的分类方式完全一致。
如果你拿到一份真实的 Information Folder,按什么顺序读最省时间? 三份官方件的版式高度一致,说明这已经是行业标准化格式:先看开头的 Key Facts 摘要页——"这是什么"(保险合同 vs 投资);接着看保证条款——到期保证与身故保证各自的比例、生效条件;再看重置(Reset)——哪个档位能重置、代价是什么;然后是费用——MER/FER、销售费选项、switch 与提前赎回的额外费用;再看受益人——如何指定、可撤销/不可撤销的区别;最后看退保与犹豫期——2 个营业日的书面撤回权、提前退保的代价。这个顺序不是本课发明的,是三家公司官方文件不约而同采用的结构,背后是全行业统一的简明披露(plain-language disclosure)要求。
收入年金可以独立购买。 Canada Life官网单独列出Income annuities及不同给付安排(Canada Life )。分离基金合同到期时选择转成年金,是取得年金的一条路径;不能据此说年金只是分离基金的一种选项。比较时要分别看当前持有的是积累期IVIC,还是已经用资本换取定期/终身收入的给付型年金。
三家官方件还有一处共同点值得记住:发行方(issuer)与产品品牌名往往不是同一个法律实体名称 ——"Manulife GIF Select"的法律发行方是 The Manufacturers Life Insurance Company,"Canada Life 分离基金"的法律发行方是 The Canada Life Assurance Company,"IAG Savings and Retirement Plan"的法律发行方是 Industrial Alliance Insurance and Financial Services Inc.。理赔文件、法律诉讼、Assuris 保障额度的认定,都是按法律发行方而不是按市场品牌名核算的,柜台工作中如果客户只报得出产品品牌名,代理人有责任核实对应的法律发行方全称。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
An advisor is preparing estate claim documents and assessing consumer protection coverage limits for a client who holds multiple segregated fund contracts marketed under different promotional series names. Which entity name must the advisor verify to properly process legal claims and determine protection limits?
一位代理人正在为一名持有多个不同推广系列名称分离基金合同的客户准备遗产理赔文件并核算消费者保障额度。代理人必须核实哪个实体名称才能正确办理法律理赔并判定保障额度?
a The commercial brand name printed on the front cover of the marketing brochure for each investment series. ✗ 错误。混淆了市场推广品牌名与法律实体名称。产品品牌名(commercial brand name)往往不是法律发行方名称,不能作为理赔诉讼和保障额度核算的法律依据。 Incorrect. Confuses commercial brand names with legal corporate entities. A commercial product brand name is frequently distinct from the legal issuer name and cannot serve as the legal foundation for claims litigation or consumer protection coverage limits.
b The name of the underlying mutual fund manager whose portfolio the segregated fund tracks. ✗ 错误。分离基金合同(IVIC)是投资者与人寿保险公司之间签署的保险合同,底层基金经理并非合同的法律发行人(issuer)。 Incorrect. A segregated fund contract (IVIC) is an insurance policy executed between the investor and a life insurance company, meaning underlying fund portfolio managers are not the legal issuers of the contract.
c The name of the managing general agency (MGA) through which the advisor originally submitted the application. ✗ 错误。总代理机构(MGA)只是销售分销渠道,不承担分离基金合同的保证兑付责任,也不是合同的法律发行方。 Incorrect. A Managing General Agency (MGA) functions merely as a distribution channel and bears no contractual guarantee obligations, nor is it the legal issuer of the contract.
d The full legal name of the issuing life insurance company stated in the Information Folder. ✓ 正确。信息文件夹(Information Folder)中载明的法律发行方(issuer)全称往往与市场品牌名不同;理赔文件、法律诉讼以及消费者保障额度的认定,均严格按法律发行方全称而非市场品牌名核算。 Correct. The full legal name of the insurer stated in the Information Folder often differs from commercial brand names; claim documentation, legal proceedings, and consumer protection coverage limits are determined strictly by the legal issuer's full corporate name rather than marketing brands.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :d
五、历史变革:为什么现在的规则跟考试口径不一样 本节回答 This section answers 回答新旧合同DSC如何并行管理及BC保险法重编后的核对原则 Parallel administration of legacy versus new DSC contracts and post-revision BC Insurance Act verification
DSC 退场对合同行政的连带影响 :seg-ch02-segregated-funds 已讲过 DSC 分两条腿走(证券侧 2022-06-01、保险侧各省 2023-06-01)。对合同条款本身的连带后果是——新单停售 DSC 后仍可能有前收费、无销售费、chargeback 或顾问收费安排;不能缩成固定两选一,保险公司理赔与退保部门现在要同时维护新旧两套逻辑:旧合同(2023 年前)仍要按原 DSC 递减表处理提前赎回费用,新合同完全不涉及这个计算。
Insurance Act 的条文本身也经历过重新编纂 :现行 BC《Insurance Act》是 SBC 2012 c.1 的合并整理版,取代了此前的 RSBC 1996 c.226。受益人指定、不可撤销受益人变更、免于债权人追索这些本篇第一节讲的核心条文,在两版之间的条号有所调整,实体效力须逐条比较,不能仅凭新旧法名称推断全无变化——这也是为什么合同条款这一层的规则读起来"长青":它依托的法律骨架虽然重新编号过,是否改变须回具体条文及生效安排核对。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
In 2021, Arthur purchased units in a segregated fund contract under a deferred sales charge (DSC) option with a seven-year redemption schedule. In 2026, he asks his advisor whether the regulatory ban on DSCs means he can now redeem those 2021 units without paying any early redemption fee. How should the advisor respond?
2021 年,Arthur 以递延销售费(DSC)选项购买了一份具有七年赎回费时间表的分离基金合同单位。2026 年,他询问代理人:监管对 DSC 的禁令是否意味着他现在赎回 2021 年购买的单位无需支付任何提前赎回费?代理人应如何回答?
a No, because contracts sold before June 1, 2023 keep their existing DSC schedules, measured from the original unit purchase dates. ✓ 正确。自 2023-06-01 起的 DSC 禁令仅禁止发行附带 DSC 的新合同;在此之前已售出的旧合同不受禁令影响,其赎回时间表可正常走完,提前赎回费用仍按既有单位购买日及原 DSC 递减表逐笔核算。 Correct. The DSC ban effective June 1, 2023 prohibits issuing new contracts with deferred sales charges; legacy contracts sold prior to that date are unaffected by the ban and run their redemption schedules normally, calculating early redemption charges based on original purchase dates and the existing DSC schedule.
b Yes, because the provincial regulator ordered all insurers to waive remaining DSC schedules on legacy contracts effective June 1, 2023. ✗ 错误。误以为 DSC 禁令具有溯及既往清零旧合同费用的效力。监管禁令针对的是 2023-06-01 起的新单,旧合同依然按原 DSC 递减表执行。 Incorrect. Mistakenly assumes the DSC ban retroactively cancels fees on legacy contracts. The regulatory ban applies to new contracts issued on or after June 1, 2023, while existing contracts continue under their original declining DSC schedules.
c No, because all pre-2023 DSC contracts were automatically converted into front-end load contracts that charge a flat exit fee on every redemption. ✗ 错误。保险公司理赔与退保部门对新旧合同采取双轨维护,旧合同仍按原 DSC 递减表处理,并不会被自动转换为另收固定退出费的前收费合同。 Incorrect. Insurers maintain parallel administration for legacy and new contracts; legacy contracts continue under their original declining DSC schedules rather than being converted into front-end load contracts charging flat exit fees.
d Yes, provided he transfers the redeemed proceeds into a new DSC segregated fund contract with the same insurer within 30 days. ✗ 错误。自 2023-06-01 起保险人已禁止发行附带 DSC 的新分离基金合同,因此不可能再转入新的 DSC 合同。 Incorrect. Because insurers have been prohibited from issuing new segregated fund contracts with DSCs since June 1, 2023, transferring redeemed funds into a new DSC contract is not permitted.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :a
六、案例(以下人物与数字均为示例,不对应真实客户) 本节回答 This section answers 回答转换触发重置、失能到期申领与即期年金退保三大实务案例 Three practical scenarios: switch triggering a reset, maturity claim under incapacity, and payout annuity surrender
案例一:Switch 触发 Reset——素里一位客户的到期日意外顺延
陈先生 5 年前在素里购买了一份 10 年期分离基金合同,假设以非注册现金存入 $60,000,此前无分配或提取导致 ACB 调整,选择 75% 到期保证。市场表现不理想,他要求把持仓从一支股票型基金转换(switch)到一支平衡型基金,代理人告知这是他本年度第一次转换、免收手续费,且这次转换会同步触发重置(reset)。转换当天市值 $63,000。
后果有两层,很多学员只看到第一层: ① 免手续费只代表这次 switch 本身不收费,但转换本身在税务上视为一次处置,$63,000-$60,000=$3,000 是资本利得;按现行 50% inclusion rate,应税资本利得为 $1,500,其他分配另报,与是否收手续费无关;② 这次转换同步触发的 reset 会把到期日从原定的第 10 年顺延为"重置日起再加 10 年"——陈先生原计划合同第 10 年到期时正好退休用这笔钱,重置之后到期日推后了 5 年,如果他没有意识到这一点,会打乱他的退休资金安排。代理人在客户提出转换请求时的告知义务,必须同时讲清楚免费次数、税务处置后果、以及是否会触发到期日顺延——只讲"这次免费"是不完整的披露。
案例二:谁能领——本拿比一份即将到期的合同背后的 POA 与提款记录
黄太太是父亲名下一份即将到期的分离基金合同的指定受益人,这份投资是父亲多年前在本拿比购买的。父亲后来因健康原因丧失行为能力,此前已签署 POA for property,把合同相关事务的决策权授权给了黄太太的哥哥。父亲两年前还做过一次部分提款。两周后合同到期,谁能领取、领多少?
正确答案分两层: 第一层,持有 POA 的哥哥可以代表父亲(持有人兼受保人)申请到期给付——黄太太此刻没有领取权,因为受益人只有在最后一位在世受保人身故后才有权领取,父亲此刻只是丧失行为能力、人还在世,合同尚未进入身故理赔流程。第二层,由于此前的部分提款已经按比例下调了保证金额,若到期时市值低于调整后的保证,应领取调整后的保证值(原保证只扣一次提款对应的减额),不是原始保证值,也不是当前市值——保证金额是动态的,withdrawal 会按比例调低它。这两层混淆——把"受益人"三个字当成领取资格的全部依据、以及忽略保证金额会因提款而下调——是这类题目最容易一起踩的两个坑。
案例三:年金开始后不可撤销——列治文一位客户的即期终身年金
黄先生,65 岁,在列治文用一笔 RRSP 资金购买了一份即期终身年金(immediate life annuity),附 20 年保证期,指定女儿为受益人,选择每月领取 $2,500。年金合同签发并开始给付三个月后,黄先生因为一次意外的大额医疗支出,想撤销合同、拿回一笔本金应急。
先核本例合同的撤销条款。 假设该传统固定给付合同没有起付后变现权且冷静期已过,便不能要求保险人退回本金。这个结论来自本例条款,不能推广成所有年金均不可取消;FCAC 明确指出部分合同可能允许起付后一段时间内付费取消。IVIC 通常可按单位价值扣费用赎回,但锁定资金及暂停交易等限制也须另外满足。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
Six months ago, Leonard used non-locked-in funds to purchase a traditional immediate life annuity that pays $1,800 per month. The contract contains no post-commencement cancellation option, and any cooling-off period has expired. Facing an unexpected home repair bill today, Leonard asks the insurer to cancel the contract and return his remaining principal. What is the outcome?
六个月前,Leonard 用一笔非锁定资金购买了一份每月给付 $1,800 的传统即期终身年金。该合同不包含起付后取消条款,且冷静期已过。今天面对一笔意外的房屋维修账单,Leonard 要求保险公司撤销合同并退还剩余本金。结果会如何?
a The insurer must refund the remaining principal minus a market value adjustment (MVA) because the funds are not locked-in. ✗ 错误。混淆了累积型年金(accumulation annuity)与传统给付型年金(payout annuity)。MVA 适用于部分允许提前退保的累积型年金,而传统即期给付型年金在起付后且无取消条款时不能退回本金。 Incorrect. Confuses accumulation annuities with traditional payout annuities. A Market Value Adjustment (MVA) applies to certain accumulation annuities that permit early surrender, whereas a traditional immediate payout annuity cannot surrender principal once payments begin when no cancellation option exists.
b The insurer will refuse, because this payout annuity has begun, its cooling-off period has passed, and it has no cancellation option. ✓ 正确。传统固定给付型年金(payout annuity)通常一经购买起付便缺乏流动性;在本例明确排除起付后付费取消权且冷静期已过的前提下,投保人不能要求保险公司撤销合同并退回本金。 Correct. Traditional fixed payout annuities generally lack liquidity once payments commence; where the contract specifically excludes a paid cancellation option after payments start and the cooling-off period has expired, the owner cannot compel the insurer to rescind the contract and refund principal.
c The insurer must allow Leonard to redeem up to 75% of his initial deposit because all insurance annuity contracts carry a statutory maturity guarantee. ✗ 错误。将分离基金(IVIC)的 75% 到期保证张冠李戴到了即期终身年金上。即期终身年金是用资本换取终身定期收入,不存在随时赎回 75% 本金的权利。 Incorrect. Misfits the 75% maturity guarantee of segregated funds (IVICs) onto an immediate life annuity. An immediate life annuity exchanges capital for guaranteed lifetime income and provides no right to surrender 75% of principal at will.
d The insurer can cancel the contract and return the principal as long as Leonard's advisor signs a verbal amendment addendum confirming the financial hardship. ✗ 错误。合同批注(amendment/addendum)必须由保险公司书面制作并由投保人签字才生效,代理人根本无权通过口头约定或自行签字来让不可撤销的即期年金退还本金。 Incorrect. Policy amendments or addenda must be drafted in writing by the insurer and signed by the policy owner to take effect; an advisor has no legal authority through verbal agreements or personal signatures to force an irrevocable payout annuity to return principal.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :b
七、考试陷阱与考场与现行对照清单 本节回答 This section answers 回答八大高频考场陷阱,涵盖免税假象、POA限制与核实豁免边界 Eight high-frequency exam traps spanning tax-free illusions, POA boundaries, and verification exemptions 本章考题 5 Question 5
Switch 免手续费不等于免税,也不等于不影响到期日 ——"免费"只代表这次转换本身没有转换费,转换在税务上仍是一次处置(可能产生资本利得),且如果同步触发 reset,到期日会顺延。题目常把"免费"当成"没有任何后果"的暗示,这是设陷阱的常见写法。BC 持续授权代理人变更既有受益人指定须法院授权;续换类似文书与新文书分别依 s.20 判断。不能凭“BC”两字就答可以换人。
到期理赔不需要死亡证明,身故理赔才需要 ——这两类理赔的申请人身份、所需文件完全不同:到期理赔找持有人或其 POA,身故理赔找受益人或遗产代表并提供充分的死亡及有权领取证明。题目把两类理赔的手续互换是常见的干扰项写法。只有非注册合同能指定候补受保人(contingent annuitant) ——注册合同因为持有人=受保人强制绑定,一旦指定受保人不能更改,也没有候补受保人这个选项。题目问"某注册 RRSP 分离基金合同能否指定候补受保人",正确答案永远是不能。纯单生、无保证期且无退款等身故选项的年金通常没有身故余额;保证期不是唯一可能的身故保护方式,须先读全部条款。
联合末存年金的受益人要等第二位年金受领人身故、且合同附保证期才可能领取 ——只要缺一个条件(合同没有保证期,或第一位受领人身故但第二位仍在世),受益人此刻都没有领取权。题目常在"第一位受领人刚身故"这个时点设陷阱,诱导选"受益人现在可以领取"。给付型年金通常缺乏流动性;是否有冷静期或起付后付费取消权依合同。考题明确排除这些权利时才答不可撤销,不可把考试口径概括当全国绝对规则。
身份识别的两项豁免只免"识别",不免"年龄证明" ——即期或延期年金资金来自注册养老金计划转移、或合同本身是注册合同时,可豁免反洗钱法下的常规身份识别程序,但受保人的年龄证明始终必须提供。题目常设置"合同满足豁免条件,代理人因此连年龄证明也没有收集"这个场景,正确答案是这一步不能省。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
Nadia is purchasing an immediate annuity funded entirely by a direct transfer from her registered pension plan. Because this transaction qualifies for an exception to routine FINTRAC identity verification, her advisor decides to skip collecting both her government-issued photo ID and any proof of her age. Which assessment of the advisor's conduct is correct?
Nadia 正在购买一份完全由其注册养老金计划直接转入资金的即期年金。由于该交易符合 FINTRAC 常规身份核实的例外条件,她的代理人决定同时省去收集其政府签发带照片身份证件和任何年龄证明的步骤。下列对代理人做法的评估哪一项正确?
a The advisor acted correctly because a direct transfer from a registered pension plan exempts the transaction from all documentation requirements, including proof of age. ✗ 错误。落入“反洗钱豁免等于豁免一切证明文件”的陷阱。身份核实例外仅针对反洗钱法下的常规身份识别,绝不豁免作为年金定价与给付核心合同事项的年龄证明。 Incorrect. Falls into the trap of believing anti-money laundering exemptions waive all documentation. Identity verification exceptions apply strictly to routine identification under AML rules, and never waive proof of age, which is essential for annuity pricing and payment calculation.
b The advisor acted incorrectly because FINTRAC never provides any identity verification exceptions for annuity contracts under any funding method. ✗ 错误。FINTRAC 对完全由合资格养老金直接转入、完全由团体寿险赔款购买或注册年金确实列有分别适用的常规身份核实例外,错在省去了年龄证明而非适用该例外。 Incorrect. FINTRAC does provide identity verification exceptions for transfers funded entirely and directly from registered pension plans, group life proceeds, or registered annuities; the error was in omitting proof of age rather than relying on the AML exception.
c The advisor acted correctly regarding age verification because the pension plan administrator has already certified her age for insurance contract purposes. ✗ 错误。在年金合同实务中,即使资金来自注册养老金计划转移而豁免反洗钱身份识别,受保人的年龄证明(proof of age)始终必须向保险公司提供,这一步不能省。 Incorrect. In annuity practice, even when funds originate from a registered pension transfer exempting AML identity verification, proof of the annuitant's age must always be provided to the insurer without exception.
d Incorrect, because the pension transfer exception covers identity verification only; proof of the annuitant's age is still required. ✓ 正确。身份识别豁免只免反洗钱法下的“常规身份识别(identity verification)”,不免“年龄证明(proof of age)”;受保人年龄直接决定年金给付计算,属于合同必要事项,始终必须提供。 Correct. Identity verification exceptions waive only routine identity verification under AML legislation, not proof of age; the annuitant's age directly determines annuity payment calculations as a fundamental contractual term and must always be provided.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :d
术语双语表
下一步 :把这一章的合同条款清单与理赔身份判断拿到题库里练手——39 道题覆盖本章每一节;条款判断题会反复考"这一条是保证还是可协商",理赔类题目会反复考"这个人此刻有没有领取权"。分离基金的产品结构与保证机制(到期保证/身故保证的计算、考试口径与现行 Assuris 数字的双口径)在 seg-ch02-segregated-funds 已经展开,与本篇合起来才是"这份合同到底怎么读"的完整答案。
本页知识卡 不看正文也能拿到这一节的核心内容:先看导读,再看图。点图放大,左右翻页。
放大 ⤢ 禁售依据与合同维护的法源不是同一部分。 先看 先读执法依据一行,再看禁售与旧合同如何分别处理。易漏 旧合同要按既有单位购买日及 DSC 表逐笔核实,不能套统一清零年。下一步 去练习区分监管题和合同维护题,再带文书问题找持牌专业人士。详情与分享 → 放大 ⤢ 同一主题下,保证内容和公司自定内容可以并存。 先看 先按行读,不要只凭主题名称判断性质。易漏 年龄上限、次数限制和 POA 内部流程都属于公司端规则,不是左栏保证内容。下一步 去练习,把每项先归类再解释理由。详情与分享 → 本站依据官方原文自撰 · 出处见正文链接