🃏 Flashcards · 3 闪卡 · 3 张 🖼 Slides · 2 幻灯 · 2 页 ✍️ Questions · 8 刷题 · 8 道
人寿保险 Life Insurance P1 必拿分 P1 Must score
ZH EN ZH + EN
先看这一章怎么考 First, how this chapter is tested
产品类型与期限匹配题:给出客户的具体风险(如房贷、收入替代、身故税负、特殊需要子女终身抚养)及现金流状况,考查以风险持续期(duration of risk)为主判据选择定期险(term insurance)、可转换定期险(convertible term)还是永久险(permanent insurance)。 Product type and duration matching questions: Presenting a client's specific risks (such as a mortgage, income replacement, death tax liability, or lifelong support for a special needs child) and cash flow situation, testing the selection of term insurance, convertible term insurance, or permanent insurance using duration of risk as the primary criterion. 多方案成本比较与续保决策题:考查累计成本分析(cumulative cost analysis)而非仅看首年保费,或当客户在定期险期满且健康恶化(如开始吸烟)时,比较按原健康等级续保与重新核保买新单的利弊。 Multi-option cost comparison and renewal decision questions: Testing cumulative cost analysis rather than merely looking at first-year premiums, or comparing the pros and cons of renewing at the original health rating versus undergoing new underwriting to purchase a new policy when an expiring term policyholder's health has deteriorated (such as starting to smoke). 保单演示件(policy illustration)合规与签字意义题:考查定期险与含非保证金额永久险演示件的区别、保证值与非保证值(guaranteed vs non-guaranteed values)的分列展示、至少两套情景(at least two scenarios)的要求,以及客户签字仅代表理解演示性质而非保司承诺回报。 Policy illustration compliance and signature significance questions: Testing the distinctions between term insurance illustrations and permanent insurance illustrations containing non-guaranteed amounts, the separate presentation of guaranteed versus non-guaranteed values, the requirement for at least two scenarios, and that the client's signature signifies only understanding the nature of the illustration rather than an insurer guarantee of projected returns. 最常丢分的陷阱(看到题干信号就警觉) Traps that cost the most marks (watch for the signal in the stem)
目标误置(把最贵最全当默认最优) Misplaced objective (treating the most expensive and comprehensive option as the default best) 题干强调客户目前收入有限或现金流紧张(tight cash flow),而选项出现保费昂贵的全额终身险组合。 The question stem emphasizes that the client currently has limited income or tight cash flow, while options feature an expensive full whole life combination. 漏算一步(只看首年保费或忽略原健康等级锁定) Missing a step (looking only at first-year premiums or overlooking original health rating lock-in) 题干出现不同期限定期险组合对比,或期满客户期间健康变差、开始吸烟却要决定续保还是重买。 The question stem presents a comparison of term insurance combinations with different durations, or an expiring policyholder whose health has worsened or who started smoking having to decide between renewal and new coverage. 管辖混淆(受益人默认可撤销与魁北克替换表格) Jurisdictional confusion (revocable beneficiary default versus Quebec replacement form) 题干出现指定配偶为受益人未声明是否可撤销,或询问魁北克与其余省份在保单替换披露表格上的差异。 The question stem mentions naming a spouse as beneficiary without specifying whether it is revocable, or asks about differences between Quebec and other provinces regarding policy replacement disclosure forms. 本章考点页:导图、要点表、7 道带逐项解析的练习 →
核实日期:2026-09-06|本页现行数字沿用上一篇需求分析算出的 CPP 遗属给付现行值(Employment and Social Develo… )与终身资本利得豁免现行值(CRA ,机制判据);「2026 市场」一节的公司与产品信息均逐条回源核实,出处见文末。
复核周期:2027-01-31。本页机制类结论(六步推荐流程、披露义务、演示件规则)长青,数字快照按上一篇的口径复核。
0. 这一篇解决什么问题
上一篇算出了一个人到底需要多少保额,这一篇接着往下走:知道要多少之后,具体推荐哪张保单、怎么把推荐讲清楚、怎么留痕 。它对应 CISRO 能力组件 c1「评估客户需求与处境」的收尾部分与 c3「落实推荐」的开端——c3 在 Life 模块占 25%,是仅次于需求分析(35%)与产品分析(30%)的第三大板块。
这一篇不重复算保额(算法见上一篇),而是讲三件上一篇没讲的事:① 怎么把一个抽象的风险(死亡/伤残/重疾/长期护理)拆成概率、严重度、持续期三个维度,反过来决定该配定期险还是永久险;② 怎么把演示件(illustration)、替换披露(replacement disclosure)、留痕说明(俗称 reason-why 信)这三份文件用对地方;③ 客户不接受建议时该怎么办,才不会让自己或客户日后陷入纠纷。这一篇帮你做到:分辨什么时候该推荐定期险、什么时候该推荐永久险;看懂一份保单演示件里哪部分是保证的、哪部分不是;以及说清楚"更换保单"和"新增保单"在披露义务上的本质区别。
一、制度设计与底层逻辑:为什么"推荐"必须留痕 本节回答 This section answers 解释为何推荐须书面留痕、披露利益冲突,且不能盲目推最贵方案 Explaining why recommendations require written documentation and conflict of interest disclosure, and why agents must not blindly recommend the most expensive option. 本章考题 1 Question 1
1. 推荐不是"卖出一张保单",是"记录一次专业判断"
需求分析算出一个数字之后,代理人面前通常有不止一种能满足这个数字的方案——不同期限的定期险组合、定期险搭永久险、要不要加附加险、保额怎么在多张保单间分配。推荐这一步的本质,是代理人在多个都"技术上可行"的方案里,替客户选出一个最贴合其处境的方案,并且说得出为什么选这个而不是别的 。这个"说得出为什么",就是这一章制度设计的核心——它不是客户服务的礼貌加分项,是代理人执业责任的证据本身。
由此产生本章第一条底层逻辑:没有书面推荐理由,会使事后重建判断依据困难。客户几年后抱怨"当初卖给我的保额不够""为什么没建议我买定期险反而卖了更贵的终身险",代理人手上如果没有一份写清楚假设、方案对比、客户最终选择的记录,就只剩"各执一词"。这正是为什么大型保司与监管机构反复强调书面化的推荐记录、演示件签字确认、替换披露文件——它们表面上是合规动作,底层逻辑是把一次专业判断变成一份可以在多年后被重新审视的证据。
2. 谁与谁在博弈:佣金结构与客户最佳利益之间的张力
这一章的执业风险集中在一个结构性矛盾上:代理人的收入通常和新单挂钩,而客户的最佳利益不一定要求开一张新单 。这个矛盾在两个场景里表现得最明显:一是客户已有一张旧保单,代理人建议"更换"成新保单——新单意味着新佣金,但对客户而言,旧保单的健康等级、既有现金价值、已过的不可抗辩期都是换新单会失去的东西;二是客户的处境只需要补一张小额定期险,但更大保额、更复杂产品结构的方案佣金更高。
受信义务(fiduciary duty)在替换场景里被格外强调,正是因为这里的利益冲突最尖锐 ——只有在真正符合客户最佳利益时才该建议更换,而不是因为新单对代理人更有利。这也是为什么"披露"在这一章被反复强调:披露不是走流程,是把这个结构性矛盾摊在客户面前,让客户带着完整信息做决定。
3. 法律后果:从纪律处分到民事追偿
推荐环节做得不到位,后果会顺着两条完全不同的路径发作。监管路径 :Insurance Council of BC 有权对未妥善履行披露义务、诱导客户不当更换保单的代理人展开纪律调查,处分从警告到吊销牌照不等;这与 ethics 模块讲的"恰当披露"义务是同一件事在 life 模块的具体应用——产品披露、替换披露、佣金分成披露,任何一项没做到都可能被认定为不公平行为。民事路径:客户或其遗属可以在理赔发生多年后,提出有关适当性与披露的索赔,但受时效与个案事实限制;E&O是否承保还要看具体保单条件。
✕
口头同意不能代替法定书面披露手续
代理人执业中最常见的自我安慰是"客户当时口头同意了,应该没问题"。口头回忆难以完整保留告知内容;应留书面记录,并完成法规要求的声明与签名:演示件有没有签字、替换披露文件有没有交付、推荐理由有没有落在纸面上。这也是为什么本章要求的每一份文件都强调"客户签字确认"或"书面说明",而不是"口头告知"。
4. 底层逻辑延伸:"推荐"要服务客户目标,不是服务"最安全"这个默认值
一个常见的误区是:既然代理人有执业风险,那就默认推荐"最保守、保额最大、条款最全"的方案,这样最不容易被追责。这个直觉是错的 。推荐的目标是匹配客户的真实处境与意愿——现金流紧张的客户被推荐了保费最高的终身险组合,即使条款再周全,也不是一份适当的推荐,反而可能构成"产品适当性"判断的失职。推荐的专业性恰恰体现在敢于对客户说"这个方案对你不合适",而不是把最贵、最全的方案包装成"最安全"。这一条会在第七节的考试陷阱里再次出现,因为它是这一章最容易被误答的一处。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
An agent completes a needs analysis for a client with a tight household budget. Worried about future liability if a claim occurs, the agent recommends the most expensive permanent life policy with maximum riders, obtains the client's verbal agreement, and keeps no written notes comparing simpler options. Where did the agent's practice fail?
一位代理人为家庭预算紧张的客户完成了需求分析。由于担心日后理赔时被追责,代理人推荐了保费最贵、附加险最全的永久寿险方案,取得了客户的口头同意,且未保留任何比较其他简便方案的书面记录。该代理人的做法错在哪里?
a Recommending the most comprehensive and expensive coverage always shields the agent from suitability complaints, provided the client agrees verbally at the time of application. ✗ 错在陷入「目标误置」与「口头同意代替书面留痕」两个陷阱。推荐的目标是匹配客户的真实处境与意愿(suitability),对现金流紧张的客户推荐保费最高的方案反而可能构成产品适当性判断失职,且口头同意不能代替书面记录。 Falls into both the 'misplaced objective' and 'verbal consent replacing written documentation' traps. The goal of a recommendation is suitability matching the client's circumstances and intentions; recommending the most expensive option to a cash-strapped client breaches suitability, and verbal consent cannot replace written records.
b The recommendation failed suitability because it ignored the client's cash flow constraints, and relying on verbal consent without written rationale leaves no evidence of the professional judgment. ✓ 正确。根据本章制度设计与底层逻辑,推荐不是默认选「最安全、最贵、条款最全」的方案,而是要贴合客户的真实处境与预算;同时必须将假设、方案对比与推荐理由写成书面记录(written record / reason-why record),口头回忆无法在日后争议中重建专业判断依据。 Correct. Recommendations must not default to the most expensive or comprehensive option, but must match the client's actual situation and budget; furthermore, assumptions, alternative comparisons, and rationales must be documented in a written reason-why record, as verbal recollections cannot substantiate professional judgment in future disputes.
c The agent only needed to document the recommendation in writing if the transaction involved replacing an existing life insurance contract. ✗ 错在缩小了书面留痕的适用范围(前提误用陷阱)。虽然保单替换(policy replacement)有强制性的专门披露表格,但任何实质性推荐都应保留书面推荐理由,否则客户日后质疑为何没买定期险而是买了更贵的终身险时将各执一词。 Unduly narrows the scope of written documentation (misapplied premise trap). While policy replacements mandate specific statutory forms, all substantive recommendations require written documentation, without which an agent cannot defend why expensive whole life was recommended over term insurance.
d Fiduciary duty only applies when an agent splits commissions with another advisor, so product suitability is entirely the client's responsibility. ✗ 错在曲解了受信义务(fiduciary duty)与适当性责任。佣金结构与客户最佳利益之间天然存在张力,评估产品适当性并如实披露是代理人的核心执业责任,不能推卸给客户。 Distorts fiduciary duty and suitability obligations. The inherent tension between commission structures and client best interests makes assessing suitability and full disclosure a core professional responsibility that cannot be shifted to the client.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :b
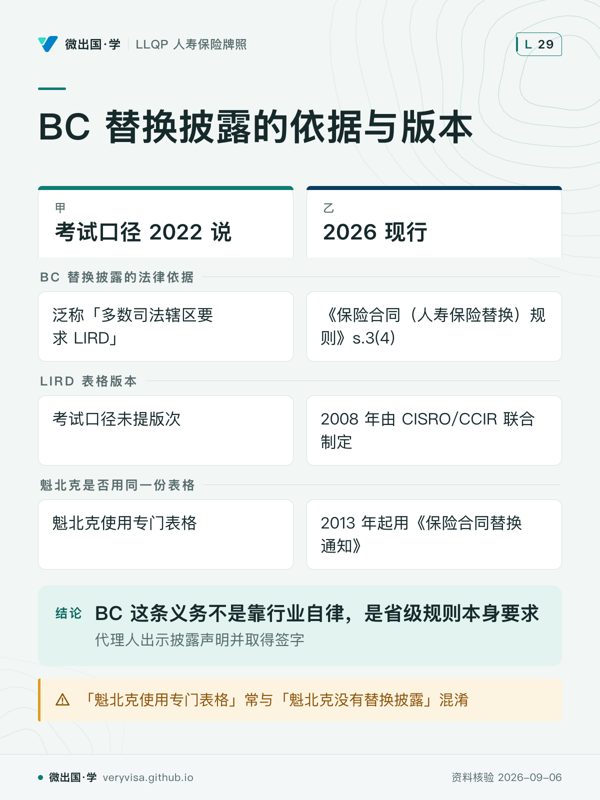
二、2026 现行政策与数字:推荐环节沿用需求分析的现行值,新增披露规则的版次 本节回答 This section answers 区分替换披露表格在全国与魁北克的适用及考试与现行法规口径 Distinguishing the application of replacement disclosure forms across Canada versus Quebec, as well as exam standard versus current regulatory standards. 本章考题 2 Question 2
这一章本身很少涉及会逐年调整的政府给付数字(那是上一篇的内容),但推荐环节里两类信息需要标注版次:一是继续沿用上一篇的现行数字来完成"从缺口到保额"的最后一步;二是披露表格与行业指引本身也有版次,用错版次会让客户拿到过期的表格。
1. 考场与现行对照表:替换披露文件的版本与依据
ℹ️
这张表和上一篇的 CPP/LCGE 表不是同一类"过期"
上一篇的数字每年按指数化机制变动,是"同一个数字换了版本";这里的三行是"同一个制度目的(防止不当更换),落地文件与依据在不同法域长得不一样"。判断方法不同:数字类问题先问"哪一年",这里的制度类问题要先问"哪个省"。
2. 演示件的"保证 vs 非保证"规则版次
CLHIA 行业指引对演示件的核心要求——保证值必须显示、非保证值必须清楚标注、非保证部分至少展示两套情景——这条规则本身是长青的行业标准(考试口径写"通常至少两套回报假设"),本页引用的具体条文表述来自二手转述,尚未逐字核对官方指引全文(Advisor.ca(转述 CLHIA Guidelin… ,置信度"较高但未逐字核对")。这条规则不受年度指数化影响,不需要每年重查,但如果客户拿到的演示件连一套"less favourable"情景都没有,这份演示件本身就不合规 ,代理人应主动向公司询问而不是直接呈给客户。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
An agent is preparing for the licensing exam and reviewing how life insurance replacement disclosure rules are described across Canadian jurisdictions, as well as the standard requirement for policy illustrations with non-guaranteed values. Which statement accurately reflects the exam standard?
一位准代理人正在备考牌照考试,复习加拿大各司法辖区关于人寿保险替换披露规则的表述,以及含非保证金额保单演示件的标准要求。下列哪项准确反映了考试口径?
a Most jurisdictions use the Life Insurance Replacement Declaration (LIRD) except Quebec, which uses its own specific replacement notice, and non-guaranteed illustrations require at least two scenarios. ✓ 正确。按考试口径,多数司法辖区要求使用寿险替换声明书(Life Insurance Replacement Declaration, LIRD),而魁北克使用专门的《保险合同替换通知》表格;含非保证金额的演示件通常至少展示两套回报情景。需注意考试口径泛称多数法域要求 LIRD,而在 BC 现行法下《保险合同(人寿保险替换)规则》s.3(4) 对出示声明与签字有明确的成文法规定。 Correct. Under the exam standard, most jurisdictions require the Life Insurance Replacement Declaration (LIRD), while Quebec uses its own specific Notice of Replacement of Insurance Contract form; illustrations with non-guaranteed values require at least two scenarios. Note that while the exam standard broadly refers to most jurisdictions using the LIRD, in BC section 3(4) of the Insurance Contract (Life Insurance Replacement) Regulation provides the explicit statutory rule for presenting the declaration and obtaining signatures.
b Quebec does not require any written replacement disclosure when a client cancels an existing policy, whereas all other provinces mandate the LIRD form. ✗ 错在「管辖混淆」陷阱,误以为魁北克不用 LIRD 就等于没有替换披露义务。魁北克自 2013 年起使用专门的《保险合同替换通知》表格,同样有严格的书面替换披露要求。 Falls into the 'jurisdictional confusion' trap by assuming that because Quebec does not use the LIRD, it has no replacement disclosure obligation. Quebec mandates its own Notice of Replacement form with equally strict written disclosure requirements.
c Because illustration rules are indexed annually like government pension benefits, agents must look up new scenario counts every calendar year. ✗ 错在混淆了「数字指数化更新」与「长青制度标准」。行业指引对演示件区分保证值与非保证值(guaranteed vs non-guaranteed values)并展示至少两套情景的要求是长青标准,不受年度指数化影响。 Confuses indexed monetary figures with evergreen regulatory standards. Industry guidelines requiring illustrations to separate guaranteed from non-guaranteed values and display at least two scenarios are evergreen standards unaffected by annual indexation.
d Even if an illustration for a non-guaranteed permanent policy shows only one optimistic projection without a less favourable scenario, the agent may present it as long as the client signs it. ✗ 错在违反了非保证演示件的基本合规要求。如果含非保证金额的演示件连一套较不利情景(less favourable scenario)都没有,这份演示件本身就不合规,代理人应主动向保险人询问而不能直接呈给客户签字。 Violates basic illustration compliance rules. If an illustration with non-guaranteed values fails to show even one less favourable scenario, the illustration is non-compliant, and the agent must contact the insurer rather than presenting it to the client for signature.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :a
三、实务流程:从"算出保额"到"客户签字接受"的六步 本节回答 This section answers 掌握六步推荐流程、产品决策树、累计成本比较与受益人默认规则 Mastering the six-step recommendation process, product decision trees, cumulative cost comparisons, and default beneficiary rules. 本章考题 3 Question 3
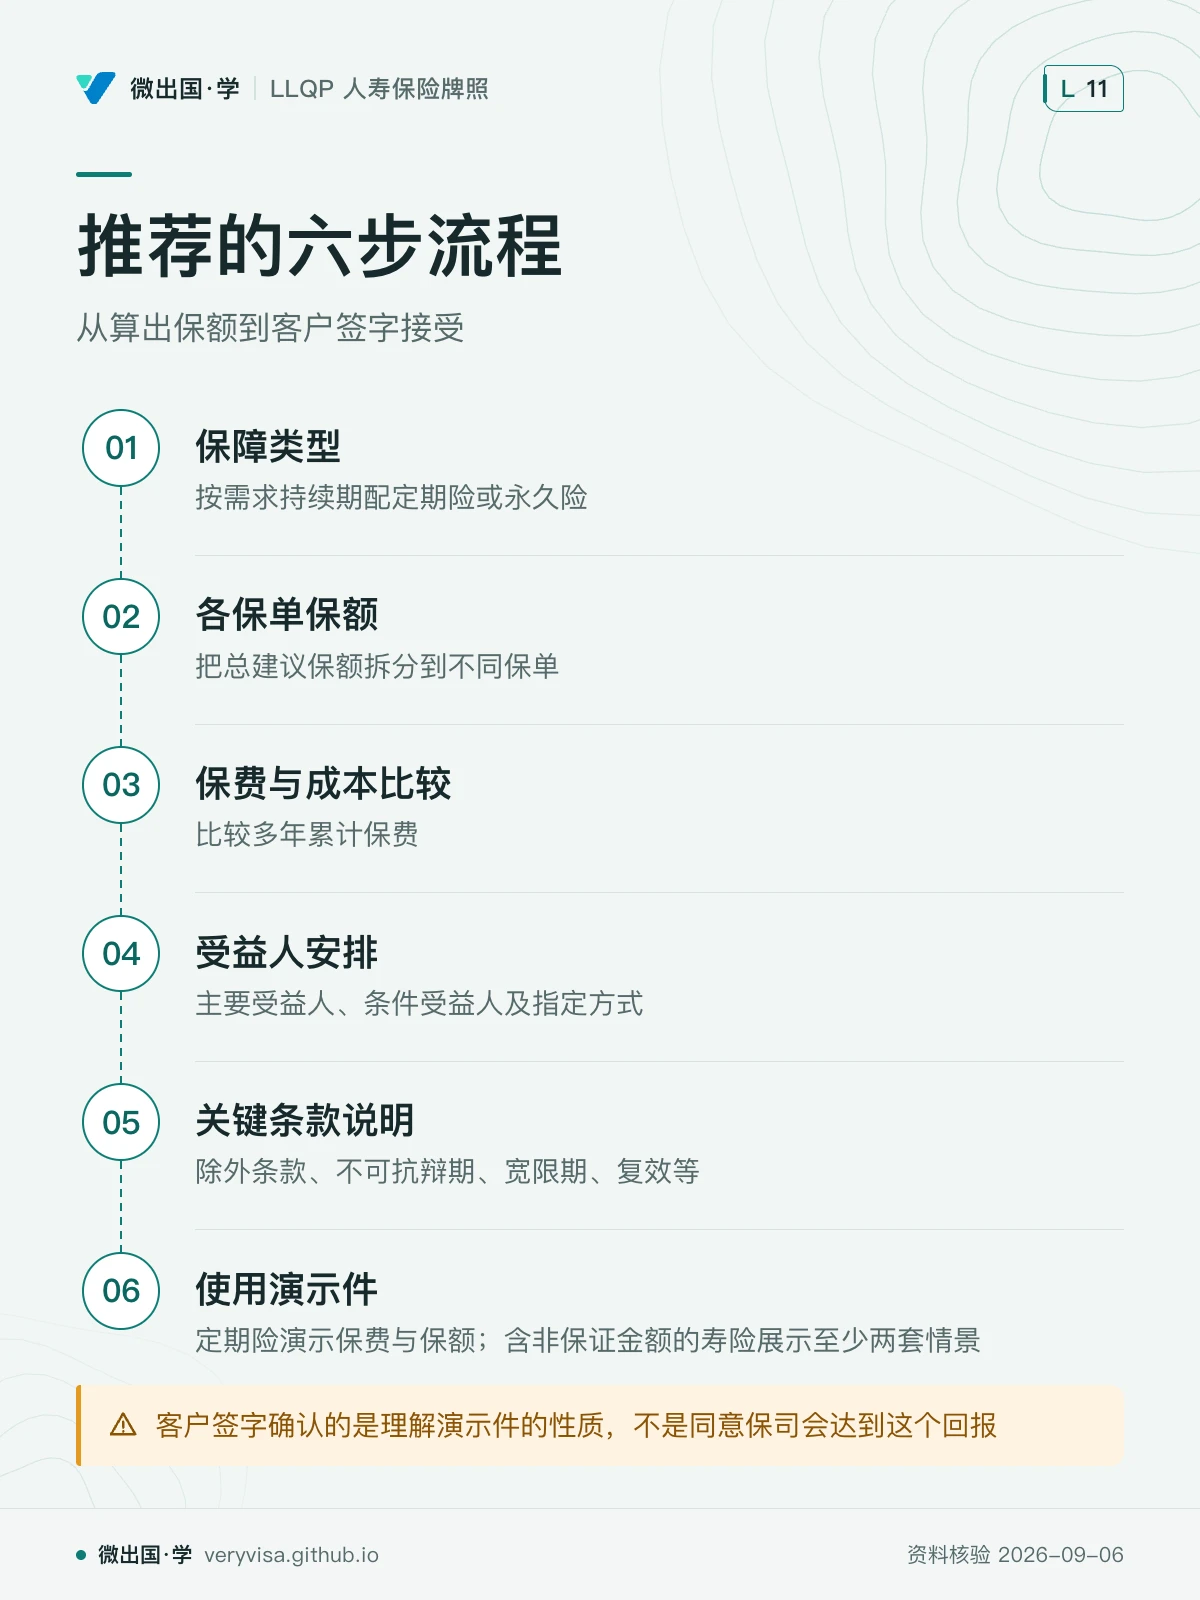
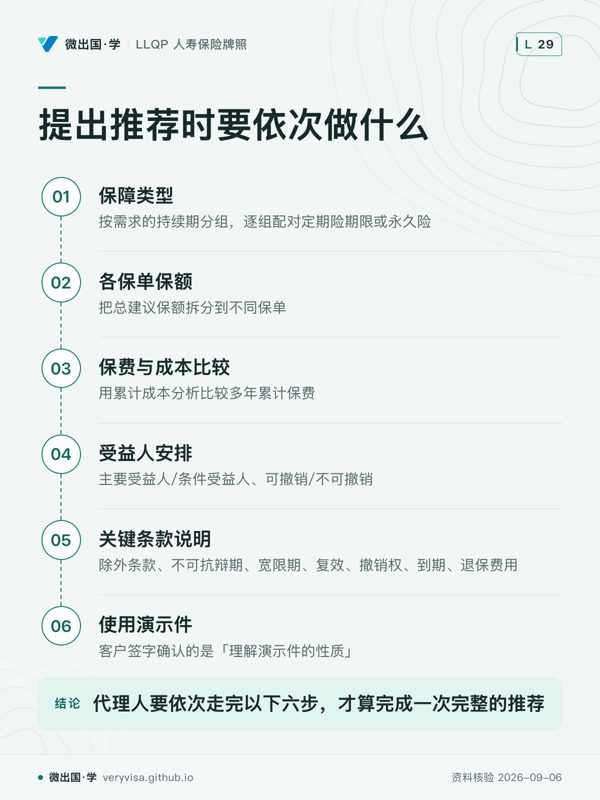
1. 提出推荐的六步流程
图:推荐的六步流程——从算出保额到客户签字接受
上一篇算出保额建议之后,代理人要依次走完以下六步,才算完成一次完整的推荐:
2. 产品选择决策树:定期险、终身险、万能寿险、团体补充,怎么分流
综合考量(bringing it all together)阶段,代理人要同时看四个维度才能落到具体产品类型:需求持续期 是主判据,投资需求、现金流与保费、配偶子女保障是三个调节维度。
需求有明确终止年限(房贷/子女预算供养期结束/收入替代到退休)?
├─ 是 → 优先定期险;现金流紧张选可转换定期险保留未来选项
└─ 否 → 需求终身存在(身故税负/慈善捐赠/特殊需要子女终身抚养)?
         ├─ 是 → 优先永久险(终身寿险或万能寿险)
         │       ├─ 已用满 RRSP/TFSA 想进一步节税或跨代传富 → 偏向分红终身险或 UL
         │       └─ 现金流波动 → 先测持续支付COI能力;万能寿险灵活缴费不等于可以长期不缴
         └─ 否(需求不确定,客户目前收入有限) → 可转换定期险;GIB是否可附加须核产品,
                 把决定权留到未来健康与收入更明朗时再转换
已有团体寿险的客户还有第五条分支:BC 团体寿险被保险人可依法指定受益人,并无一般性的「只能指定家属」限制、保额通常有上限、离职后转换权只受行业自律指引约束(详见上一篇既有保障核对一节)——团体险是否已足够,要按实际保障缺口与持续性判断,代理人推荐个人险时要先把团体险的可转换性与保额上限算清楚。
3. 读懂一份保单演示件:保证栏和非保证栏分别在说什么
定期险的演示件很简单,只有每个保单年度的保费与保额两栏,因为定期险没有现金价值或分红这类会随投资回报波动的部分。永久险的演示件复杂得多 ,除了保费与身故给付,还会列出账户价值、现金解约价值(CSV)与分红或投资回报的多年投影——这些投影栏目不是预测,是演示机制怎么运作。
读演示件时抓两件事:① 哪些数字前面标了"保证",哪些标了"非保证"或用了斜体/星号提示;② 非保证部分是不是至少给了两套情景。客户签字确认的意义正在于此 ——签字不是同意购买,是确认自己理解了"表格上那些好看的长期数字不是保司的承诺"。代理人如果只把演示件当成促成签单的销售工具而不解释这层区别,一旦未来实际回报低于演示的乐观情景,客户的第一反应通常是"当初你说会有这么多",而历史上的消失保费争议正说明了这种误解的风险(见第五节)。
4. 更换保单:披露、时限、绝不能做的一件事
当推荐方案涉及放弃或替换客户已有的保单 去买一张新保单时,规则比普通新增推荐严格得多,原因回到第一节的核心矛盾——新单意味着新佣金,客户可能因此损失旧保单的既得利益。
先分清两种不当行为 :转保(churning)指用误导或不实信息说服客户在同一家保司内更换保单或提取现金买新单;掉保(twisting)是同样的手法,但发生在不同保司之间。两者都违反代理人的受信义务,区别只在于是否跨保司。
披露义务的三层落地 :① 在着手属于法规所定义替换的新申请之前,代理人须向申请人讲解声明,取得申请人签字;被保险人与申请人不同者也须签字(BC 依据前述省级规则),并附一份书面说明,讲清楚更换的理由、新保单的优点、新保单可能不赔付的情形(例如新的两年不可抗辩期重新起算);② 除魁北克使用专门表格外,其余省份统一用 LIRD;③ BC替换声明要求先确认新单生效且客户接受,再取消旧单,以免保障空窗;发生损失后的具体责任须依事实判断,不能预先判定总由代理人主要承担。
⚠️
"客户自己要求换"不能免除代理人的披露义务
常见的误解是:只要是客户主动提出要换保单,代理人就不需要走替换披露流程。实际上,无论是谁先提出更换,若交易落入 BC 规则 s.1 的替换定义,披露义务成立;合同原有权利的行使、被替换的是年金、改成团体险等有明列排除——它保护的是客户的知情权,不是用来判断"谁的主意"。
5. Reason-why 记录:不是替换才要写,任何推荐都该留一份
"reason-why"不是某个法定表格的名字,而是这个行业对推荐留痕这件事本身 的通俗说法——把"我为什么推荐这个方案,而不是另一个方案"写下来的书面记录。它和替换披露的书面说明是近亲,但适用范围更广:替换披露只在换保单时强制要求,reason-why 记录该在每一次实质性推荐时都做,不管有没有旧保单要换。
一份能站得住脚的 reason-why 记录,通常包含四块内容:
客户处境摘要 :需求分析用的关键假设(收入、家庭结构、既有保障),三言两语即可,不需要重抄整份需求分析表;考虑过的方案与为什么没选 :例如"曾考虑纯定期险方案,但客户明确表达希望部分保费能积累现金价值用于退休补充,故改为定期险+小额分红终身险组合";最终推荐与匹配到的具体需求 :每一份保单对应解决了六要素清单里的哪一项;客户的回应 :接受、部分接受、还是完全拒绝,以及客户拒绝时代理人是否已把相应风险讲清楚。
这四块内容不需要另立一份复杂表格,很多公司的需求分析软件或投保系统会自带"推荐说明"栏位,把它填完整就够。它真正的价值不在签单那一刻,而在几年后——它有助于证明当时的判断、依据与客户回应。
6. 客户拒绝推荐:留痕比说服更重要
客户完全有权利不接受代理人的建议——选更低的保额、只买定期险不买附加险、甚至完全不投保。代理人这时候的责任不是"说服到底",而是确保客户是在充分理解风险的前提下做出的选择,并把这一点记录下来 。正确的处理顺序是:① 讲清楚建议方案解决的是哪些具体风险;② 讲清楚客户选择的方案会留下哪些缺口未被覆盖;③ 把客户的最终选择、以及"已就缺口进行说明"这一事实记入 reason-why 记录,必要时请客户签字确认已理解差异。
代理人不能做的两件事 :一是不顾客户明确表态、反复施压促成更大保额(可能构成不当销售);二是客户拒绝后就什么都不记录、下次见面从零开始(一旦日后出现理赔纠纷,代理人手上没有任何证据证明当年讲清楚过风险)。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
A married couple living in British Columbia needs life insurance to cover two distinct needs: a twenty-year mortgage and capital gains tax payable only upon the death of the second spouse. They also plan to name each other as primary beneficiaries without specifying whether the designation is revocable or irrevocable. Which approach aligns with the six-step recommendation process?
一对居住在 BC 省的已婚夫妇需要人寿保险来覆盖两项不同的需求:一笔二十年期的房贷,以及仅在第二位配偶身故时才须缴纳的资本利得税。他们还打算互相指定对方为主要受益人,但未注明该指定是可撤销还是不可撤销。下列哪种做法符合六步推荐流程?
a Combine both needs into a single twenty-year term policy to minimize first-year premiums, and inform them that spousal beneficiary designations are automatically irrevocable across Canada. ✗ 同时犯了「产品误配」和「管辖混淆」两个错误。第二位配偶身故才触发的税负属于终身需求,不能用二十年定期险覆盖;且除魁北克外,BC 省默认所有受益人指定(包括配偶)都是可撤销的(revocable beneficiary)。 Commits both product mismatch and jurisdictional confusion errors. Tax triggered upon the death of the second spouse is a permanent lifelong liability that cannot be covered by a twenty-year term policy; furthermore, outside Quebec, BC treats all beneficiary designations (including spouses) as revocable by default.
b Use a single individual permanent policy for the total amount so they never face renewal rate jumps, and name their estate as beneficiary to avoid probate fees. ✗ 错在把短期房贷需求混入永久险导致客户多付保费,且颠倒了遗嘱认证影响(probate implication):指定遗产(estate)为受益人恰恰会使身故金进入遗嘱认证程序并产生认证费。 Errs by bundling a temporary mortgage need into permanent coverage causing excessive premium costs, and reverses probate implications: designating the estate as beneficiary subjects proceeds to probate administration and probate fees.
c Match a twenty-year term policy to the mortgage and a joint last-to-die permanent policy to the tax at second death, and explain that the spousal designation is revocable by default in BC. ✓ 正确。按六步推荐流程(making the recommendation),应按需求持续期(duration of risk)拆分保单:有明确终止年限的二十年房贷配定期险,可递延至末位配偶身故的税负配联合末身故(joint last-to-die)永久险;同时在 BC 省未特别声明时,配偶受益人指定默认为可撤销。 Correct. Under the six-step recommendation process, policies should be matched to duration of risk: a twenty-year mortgage with a definite horizon is paired with term insurance, while tax liabilities deferred until second death are paired with a joint last-to-die permanent policy; additionally, in BC, spousal beneficiary designations are revocable by default unless explicitly declared otherwise.
d Recommend replacing any group coverage they hold before applying, and ask them to sign the illustration to guarantee the projected dividends. ✗ 错在「流程顺序错误」与曲解演示件签字含义。绝不能在新单生效前取消既有保障,且客户在演示件(policy illustration)上签字仅确认理解其非保证性质,而非保证获得预计红利。 Commits an inverted process error and misinterprets the meaning of signing an illustration. Existing coverage must never be cancelled before the new policy is in force, and signing an illustration confirms only understanding of its non-guaranteed nature, not a guarantee of projected dividends.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :c
四、2026 市场:推荐环节已经软件化,但底层判断没变 本节回答 This section answers 理解电子投保、智能核保与演示软件如何辅助而不替代代理人判断 Understanding how electronic applications, automated underwriting, and illustration software assist but do not replace agent professional judgment.
保险人已提供数字投保与演示工具——大型保司与第三方软件商把这一章的比价逻辑、核保问卷、演示件生成做成了一体化平台。以下产品与机制均逐条回源核实,只写机制,不写促销数字:
电子投保与即时核保 :iA Financial Group 的 EVO 平台把电子投保问卷、定制化核保与保费/保障比较工具合在同一个代理人端流程里,多数客户可在柜台当场拿到承保决定(iA Financial Group );截至 2026 年 4 月,该公司约半数新单已经走这套数字化流程,覆盖定期险与永久险,自助功能已扩展到受益人变更与账单调整(iA Financial Group )。它对应考试口径哪个步骤:把 11.5「提出推荐」到保单交付这条链路里原本要跑多个环节的动作合并成了一个界面。
Manulife 的 AI 核保引擎 MAUDE(MAUDE 的本页数据以2026官方新闻稿为限)配合改版电子投保表,截至 2025 年底约 58% 符合条件的案子由 AI 自动完成核保,最快两分钟出结果,新版投保表的医疗问题最多减少40%,因个案问卷而异(Manulife(经 Newswire 分发;manul… )。它对应考试口径哪个步骤 :ch09 讲的核保判断逻辑(家族病史、生活方式风险如何影响加费)现在部分由算法自动执行,但"哪些因素会影响核保结论"这条知识点本身没有变,变的只是谁在做判断。
演示件工具 :加拿大保险业广泛使用第三方演示件软件(如 Equisoft/illustrate 这类平台),供多家保司与代理人共用,用于快速生成保费与保障比较、跑不同情景(Equisoft(第三方软件商,供多家加拿大保司使用,非… )——考试口径要求学员在 11.5.3 节手算的累计成本比较,正是这类软件在真实柜台自动出具的报表,理解手算逻辑仍然重要,因为代理人要能向客户解释"系统为什么推荐这个组合",而不是把软件当黑箱。
披露文件的电子化 :LIRD、替换披露说明、演示件签字确认这些原本纸质流程的文件,目前普遍随电子投保平台一起以电子签名方式完成——机制要求(谁必须签、什么时候签、内容要写什么)没有变,变的只是签名的载体从纸笔变成了平板或电脑。待深研:具体某几家保司的电子签名替换披露流程细节、以及是否所有保司的 e-App 平台都已内置 LIRD 电子化流程,尚未逐一核实。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
An agent uses an electronic application platform integrated with automated underwriting and third-party illustration software that generates multi-year cost comparisons and electronic replacement disclosure forms on a tablet. Which statement correctly describes the agent's responsibility when using these digital tools?
一位代理人使用集成了自动核保与第三方演示软件的电子投保平台,在平板电脑上自动生成多年成本比较表与电子版替换披露文件。在使用这些数字化工具时,下列哪项正确描述了代理人的责任?
a Because the software automatically calculates the cumulative cost analysis, the agent no longer needs to explain why a specific combination of policies is recommended. ✗ 错在把演示软件当成免除解释义务的黑箱。虽然第三方演示件软件能自动生成累计成本分析(cumulative cost analysis)报表,代理人仍必须理解底层逻辑并向客户讲清楚系统为什么推荐该组合。 Treats illustration software as a black box exempting the agent from explaining recommendations. Although third-party software calculates cumulative cost comparisons automatically, the agent must understand the underlying rationale and explain why a specific combination is recommended.
b Automated tools change the speed and execution of underwriting, but judging risk duration, suitability, and replacement disclosure remains the agent's job. ✓ 正确。电子投保(e-application)、AI 自动核保与演示件工具改变的只是执行方式与载体,但判断客户需求持续期、评估换单是否符合客户最佳利益、履行替换披露与完成电子签名确认的核心执业责任完全没有改变。 Correct. Electronic applications, automated underwriting, and digital illustration tools change the operational speed and delivery medium, but evaluating risk duration, suitability, replacement disclosure, and obtaining informed signatures remain core professional responsibilities of the agent.
c Collecting an electronic signature on a tablet waives the requirement to deliver a written explanation of the pros and cons of replacing an existing policy. ✗ 错在混淆了签名载体与法定披露内容。披露文件电子化只是把纸笔签字变成平板或电脑签字,谁必须签、何时签以及替换书面说明的内容要求并未减少。 Confuses the medium of signature with statutory disclosure content. Digitizing documents merely changes ink on paper to a screen signature; rules specifying who must sign, when they must sign, and what written explanations are required remain unchanged.
d When an automated underwriting platform issues an approval within two minutes, the two-year incontestability period on the new policy is automatically waived. ✗ 错在编造了即时核保的法律后果。核保速度加快(如两分钟出结果)并不改变保单条款,新保单依然适用法定的两年不可抗辩期(incontestability period)。 Fabricates legal consequences of instant underwriting. Faster automated decisions do not modify policy provisions, and the new contract remains subject to the statutory two-year incontestability period.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :b
五、历史变革:从"消失保费"丑闻到强制两套情景 本节回答 This section answers 从消失保费争议理解为何非保证演示必须展示至少两套情景 Understanding why non-guaranteed illustrations must display at least two scenarios based on lessons from the vanishing-premium controversy.
其一,消失保费争议说明演示假设不能变成承诺。 考试口径借此提醒:非保证红利不足时,客户可能仍须缴费。G6 的现有官方文本要求清楚区分保证与非保证金额,并对非保证寿险演示展示至少两套情景;它是行业指引,不应被写成全国统一的客户签字法条。这里不将争议精确起始年代或指引出台的单一因果写成已核实历史。
其二,LIRD 的出现,是行业自己意识到"换保单"这个环节风险最集中之后主动补的洞。 2008 年由 CISRO 与 CCIR 联合制定统一表格之前,各省对替换披露的要求并不统一,转保与掉保长期是纪律处分的高发领域;2023 年的修订征求意见,方向是把"信息讲清楚"的责任进一步压实到代理人身上——这条演变说明监管的方向是持续收紧,而不是一次性定了规则就不再变化。
其三,推荐流程的自动化,改变的是执行方式,没有改变判断逻辑。 核保决定可以两分钟出结果,演示件可以由软件自动生成,但"这个客户的需求持续期是多久、该配定期险还是永久险、换保单是否真的对客户有利"这几个判断,仍然只能由代理人做出,也仍然只能由代理人对结果负责。这正是这一章存在的意义:考试口径要求学员手走一遍完整流程,是为了让学员在软件给出结论时,仍然知道那个结论是不是合理的。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
A client reviewing a participating whole life illustration asks whether the projected dividends will eventually pay all future premiums so she can stop paying out of pocket permanently. Based on lessons from historical vanishing-premium disputes and industry illustration guidelines, how should the agent respond?
一位客户在查看分红终身寿险演示件时询问,预计红利是否最终能抵缴未来所有保费,从而让她永久停止自掏腰包缴费。基于历史上「消失保费」争议的教训及行业演示件指引,代理人应如何回应?
a Confirm that once the client signs the policy illustration, the insurer is legally bound to cover any future premium shortfall if dividends decline. ✗ 错在把非保证演示当成保险人承诺。客户在保单演示件(policy illustration)上签字只是确认自己理解非保证数字不是承诺,绝不代表保险人会兜底红利差额。 Treats non-guaranteed illustrations as insurer guarantees. Signing a policy illustration confirms the client understands non-guaranteed figures are not promises, and never implies the insurer will cover dividend shortfalls.
b Explain that dividends are non-guaranteed, show at least two scenarios including a less favourable one, and note she may still need to pay premiums. ✓ 正确。历史上的消失保费争议(vanishing-premium disputes)说明演示假设绝不能变成承诺:非保证红利不足时客户仍须继续缴费,因此行业指引 G6 要求清楚区分保证值与非保证值(guaranteed vs non-guaranteed values),并对非保证金额展示至少两套情景。 Correct. Historical vanishing-premium disputes demonstrated that illustration projections must never be represented as guarantees: if non-guaranteed dividends decline, the policyholder must continue paying premiums out of pocket; therefore, Guideline G6 mandates distinguishing guaranteed from non-guaranteed values and showing at least two scenarios for non-guaranteed amounts.
c Replace the participating policy illustration with a single-scenario projection showing only the historical average dividend rate of the participating account. ✗ 错在违反了非保证演示件至少展示两套情景的规则,且过去的分红账户历史表现并不保证未来回报。 Violates the rule requiring non-guaranteed illustrations to show at least two scenarios, and past performance of the participating account does not guarantee future dividend returns.
d Advise the client that vanishing premiums are guaranteed under provincial replacement regulations as long as the LIRD form is signed before policy delivery. ✗ 错在混淆了寿险替换声明书(LIRD)与分红演示规则。LIRD 用于规范保单替换披露,与保证红利抵缴保费毫无关系。 Confuses the Life Insurance Replacement Declaration (LIRD) with dividend illustration rules. The LIRD regulates replacement disclosures and has nothing to do with guaranteeing dividend-offset premiums.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :b
六、案例:三个最容易在"推荐"这一步出错的场景 本节回答 This section answers 应对期满健康恶化续保、换单利弊对照表与客户折衷购买保额的留痕 Handling renewals when health deteriorates at expiry, replacement pros-and-cons tables, and documenting client compromise on coverage amounts. 本章考题 4 Question 4
案例 A:Barry 的续保困境——保留旧保单反而更便宜(示例)
素里的 Barry,38 岁投保时买了一张 $250,000 二十年定期险,月保费 $35。到 58 岁二十年初始保障期届满时,他的健康状况已经变差(期间开始吸烟),面临两个选择:续保原保单 ——续保保费按原发单时的健康等级计算,与他现在的吸烟状况无关,只是保费按年龄上涨;重新投保一张新单——新单必须按他现在(吸烟者)的健康状况核保,新单可能更贵、被加费或拒保,但也须与旧单预定续保费率实际比较,不能仅凭吸烟就断定价格顺序。
推荐环节的关键动作 :代理人这时候的专业价值,不是急着卖一张新单赚佣金,而是先算清楚两条路径的多年累计成本,把"续保锁定原健康等级"这个反直觉的机制讲给客户听。常见错法:代理人默认"新单总是更划算"直接推荐重新投保,却没有意识到 Barry 的健康状况变化恰恰是续保对他更有利的原因。
案例 B:一份完整的替换利弊对照表(示例)
列治文的 Priya,45 岁,五年前买过一张 $300,000 分红终身险,现金价值已积累到 $18,000。新代理人建议她退保旧单、改买一张保额更高、附加更多重疾保障的万能寿险。在做出决定前,代理人必须把以下对照表交给客户并留痕:
这份表格本身,就是 reason-why 记录的核心内容 ——它逼着代理人把"为什么建议换"或"为什么建议不换"摊在纸面上,而不是凭一句"新产品更好"就让客户签字。本例中,若 Priya 的核保结果显示健康状况良好,重疾附加确实覆盖了她此前没有的风险,更换仍然可能是合理建议——关键是这份对比留了痕,而不是这个决定本身对错。
案例 C:客户拒绝推荐保额,代理人如何收尾(示例)
北温的 Marcus,本例另假设经完整需求分析建议新增保额 $600,000,但受限于家庭现金流,他只愿意购买 $300,000。代理人的正确收尾:① 明确告知客户 $300,000只覆盖经核定总缺口的一部分,具体分配给房贷或收入替代须另列;不能未给房贷余额便承诺两项已全覆盖;② 把双方讨论过的两个方案($600,000 全额 vs $300,000 折衷)与 Marcus 的最终选择记入 reason-why 记录;③ 建议未来收入提高或现金流改善后重新评估,而不是就此不再追踪。常见错法 :代理人因为客户只买了一部分而不再解释缺口,或者把"客户自己选的"当作免责理由却没有任何书面记录支持这一点。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
An agent conducts a thorough needs analysis showing a client has a $600,000 insurance gap covering both a mortgage and family income replacement. Due to budget constraints, the client insists on purchasing only $300,000 of term coverage. How should the agent finalize this recommendation?
一位代理人经过完整的需求分析,算出客户有 $600,000 的保额缺口(涵盖房贷与家庭收入替代)。但由于预算有限,客户坚持只购买 $300,000 的定期寿险。代理人应如何完成这次推荐的收尾?
a Refuse to submit the application for $300,000 because accepting half of the needed coverage exposes the agent to automatic disciplinary action. ✗ 错在忽视了客户的自主决定权。客户完全有权因现金流限制只买部分保额,代理人的责任是讲清未覆盖的风险缺口并做好书面留痕,而不是拒不受理或强行施压。 Disregards the client's autonomy. Clients have the right to purchase partial coverage due to cash flow limits; the agent's duty is to explain uncovered gaps and document the decision in writing, not to refuse the application or apply pressure.
b Assure the client in writing that $300,000 is sufficient to fully cover both the mortgage and income replacement needs so the client feels comfortable signing. ✗ 错在做出虚假承诺。在 $600,000 总缺口只买了 $300,000 的情况下,不能承诺两项需求已全部覆盖,必须明确指出只覆盖了一部分缺口。 Makes a false assurance. When $300,000 is purchased against a $600,000 gap, the agent cannot claim both needs are fully met, but must explicitly state that only a portion of the gap is covered.
c Submit the $300,000 application without recording the original $600,000 calculation, since the lower amount was the client's own choice. ✗ 错在把「客户自己选的」当作免除留痕的理由。如果不记录最初建议的 $600,000 方案及风险说明,日后发生理赔纠纷时代理人将没有任何证据证明当年提示过缺口。 Treats client choice as an excuse to omit documentation. Failing to document the recommended $600,000 plan leaves the agent with no evidence to prove that the risk gap was explained if disputes arise upon a claim.
d Explain that $300,000 leaves part of the gap uncovered, record both the $600,000 recommendation and the $300,000 choice in the reason-why record, and plan a later review. ✓ 正确。当客户只接受部分推荐保额时,代理人应:① 明确告知 $300,000 只覆盖核定总缺口的一部分;② 将双方讨论过的 $600,000 全额方案与 $300,000 折衷选择记入推荐留痕记录(reason-why record);③ 建议未来收入或现金流改善后重新评估。 Correct. When a client accepts only partial coverage, the agent must: 1) explain that $300,000 covers only part of the assessed gap; 2) record both the $600,000 recommendation and the $300,000 compromised choice in the reason-why record; and 3) recommend reviewing coverage when income or cash flow improves.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :d
七、考试陷阱与考场与现行对照清单 本节回答 This section answers 识别八大高频考试陷阱与考场对柜台的三项双口径差异 Identifying eight high-frequency exam traps and three dual-benchmark differences between exam standard and counter practice. 本章考题 5 Question 5
以下每条对应 CISRO 公开样题中"落实推荐"相关题目的考点与陷阱形态,按版权边界只写形态,不复述题干。
把"最安全/保额最大"当成默认正确答案 (目标误置)。推荐要匹配客户的真实处境与意愿,不是机械地推荐条款最全、保额最高的方案——现金流紧张的客户被推荐保费最高的方案,即使条款周全也不是适当推荐。
联合末身故保单被无差别推荐给"需要传给子女"的需求 (产品误配)。先判断资产转移是否符合配偶或配偶信托展期;寿险本身不递延资产税负。第一人死亡即有税款时,不能只靠末身故给付。
只比较首年保费,忽略续保跳涨 (漏算一步)。累计成本分析要看多年总保费,短期定期险起价低但续保跳涨可能更剧烈,只看首年数字会得出错误的"更省钱"结论。
受益人默认可撤销被误当成"配偶除外" (管辖混淆)。除魁北克外,全国默认所有受益人指定都是可撤销的,即使指定的是配偶——魁北克CCQ2449针对遗嘱以外书面指定已婚或civil union配偶设默认不可撤销;另有明示可撤销则从其约定,同居伴侣不因同居自动适用,题干出现"魁北克"才适用这条例外。
转保(churning)与掉保(twisting)分不清同司/跨司 (同类不同规则)。两者手法相同,区别只在于是否发生在同一保司内——题干出现"同一家公司内部换单"对应 churning,跨公司对应 twisting。
误以为客户主动要求更换就不需要替换披露 (前提误用)。无论谁先提议更换,仍须有购入新保险并符合当地替换定义;BC s.1 的明列排除不能忽略,与"谁的主意"无关。
在新单生效前取消原保单 (流程顺序错误)。正确顺序永远是:新单正式生效并被客户接受之后,才能取消原保单——反过来做会造成保障空窗期。
误以为魁北克没有替换披露义务 (数字/制度过期或混淆)。魁北克 2013 年起使用专门的《保险合同替换通知》表格,不是没有替换披露,只是不用 LIRD 这份全国通用表格。
考场与现行对照清单(考场 vs 柜台) :① BC 替换披露的法律依据——考场答考试口径泛称"多数司法辖区要求 LIRD"即可,柜台执业要知道 BC 有专门的省级规则(s.3(4))而非仅靠行业自律;② 演示件"至少两套情景"的规则——考试口径通常至少两套的提示,与 G6 针对非保证金额的范围并读;全保证产品不能硬套非保证情景;③ Reason-why 记录——考试口径不点名这个说法,但它是"恰当披露+建档"这条 ethics 义务在 life 模块的具体执行方式,考场按"披露与建档义务"作答,柜台就是写这份记录本身。
边学边测 :本章题库共 32,覆盖三层难度与四道以上情景推荐题。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
A client approaches an agent and asks on his own initiative to cancel his five-year-old permanent life policy with Company X and buy a new universal life policy with Company Y. Which statement correctly identifies the regulatory rules governing this request?
一位客户主动找到代理人,提出想退掉自己在 X 公司买了五年的永久寿险保单,改买 Y 公司的一张新万能寿险保单。下列哪项正确指出了适用该请求的监管规则?
a Because the client initiated the request himself, the agent is exempt from completing replacement disclosure documents. ✗ 错在「前提误用」陷阱。无论谁先提议更换保单,只要交易符合保单替换(policy replacement)定义,代理人就必须履行替换披露义务,保护客户的知情权与谁的主意无关。 Falls into the 'misapplied premise' trap. Regardless of who initiates the replacement, if the transaction meets the statutory definition of a replacement, the agent must complete disclosure documents; consumer protection does not depend on who proposed the change.
b If the agent uses misleading comparisons to induce this cross-company replacement, the misconduct is defined as churning rather than twisting. ✗ 错在「同类不同规则」陷阱,混淆了转保(churning)与掉保(twisting)。同一家保险公司内部诱导换单是 churning,跨不同保险公司(如从 X 公司换到 Y 公司)则是 twisting。 Falls into the 'similar terms with different rules' trap, confusing churning with twisting. Inducing a replacement within the same insurer is churning, whereas replacing across different insurers (such as Company X to Company Y) is twisting.
c Replacement disclosure must be completed before the new application proceeds, and the Company X policy is cancelled only after the Company Y policy is in force and accepted. ✓ 正确。即便客户主动提出跨司换单,代理人仍须在着手新申请前讲解替换声明并取得签字、附上书面利弊说明,且必须等新保单正式生效并被客户接受后才能取消原保单,以防出现保障空窗期。 Correct. Even if client-initiated across insurers, the agent must explain the replacement declaration, obtain signatures, and provide written pros and cons before proceeding, and the existing policy must only be cancelled after the new policy is in force and accepted, preventing a coverage gap.
d The agent should cancel the Company X policy immediately so the client can redirect the saved monthly premiums toward paying for the new Company Y application. ✗ 错在「流程顺序错误」陷阱。在新保单生效前取消原保单会让客户在核保期间失去保障,一旦新单被拒保或加费将造成无法挽回的损失。 Falls into the 'inverted process' trap. Cancelling the existing policy before the new one is in force leaves the client uninsured during underwriting, risking irreparable loss if the application is declined or rated.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :c
术语双语表
注意:本页标为「待深研」的一项 本节回答 This section answers 明确电子签名替换披露流程中已核实的机制与待核实的保司细节 Clarifying verified mechanisms and insurer-specific details under investigation in electronic signature replacement disclosure workflows.
各保司电子签名替换披露流程的具体细节 ——LIRD、书面说明与演示件签字确认是否已在所有主流保司的电子投保平台内置为标准化电子签名流程,只核实了机制存在(披露义务本身未变),未逐一核对各保司平台实现细节。
节末检索小测 · 先别往回翻,凭记忆作答 Quick recall check: answer from memory before scrolling back
When an agent processes a policy replacement using an insurer's electronic application portal, which aspect of the replacement disclosure obligation remains constant regardless of how a specific insurer's software platform is configured?
当代理人通过保险人的电子投保平台办理保单替换时,无论具体某家保险人的软件系统如何配置,替换披露义务的哪一方面始终保持不变?
a The core duties of who must sign, when signatures are obtained, and what written explanation is given stay the same under electronic signature. ✓ 正确。无论各家保司电子投保平台(e-application)内置的电子签名流程细节如何,替换披露的核心机制要求(谁必须签字、在着手新申请前签字、书面说明更换利弊等)完全没有改变,变的只是签名的载体。 Correct. Regardless of how an insurer's electronic application platform configures e-signature steps, core replacement disclosure requirements (who must sign, obtaining signatures before proceeding with the new application, providing written pros and cons) remain identical; only the signature medium changes.
b Electronic portals eliminate the need for the insured person to sign the replacement declaration when the insured is different from the policy applicant. ✗ 错在违反了替换声明的签字主体要求。根据替换披露规则,当被保险人与申请人不同时,两者均须签字,电子化流程并不会免除被保险人的签字义务。 Violates signature requirements for replacement declarations. When the life insured and the applicant are different persons, both must sign; digital processes do not waive the signature of the life insured.
c Using an electronic signature automatically shortens the client's right to rescind a replacement application in British Columbia from twenty days to two days. ✗ 错在篡改了法定撤销权期限。BC 省替换申请自签署替换声明起享有 20 天书面撤回权(right of rescission),电子签名不会缩短该法定冷静期。 Distorts statutory rescission timeframes. In BC, a replacement application carries a statutory twenty-day right of rescission from signing the replacement declaration, and electronic signatures do not shorten this cooling-off period.
d Digital platforms allow the agent to skip the written reason-why comparison as long as the LIRD checkbox is clicked online. ✗ 错在以为勾选电子表格即可免除书面利弊说明。替换披露要求除了签署声明表格(LIRD),还必须附上一份书面说明(written explanation / reason-why record),讲清楚更换理由、新单优点与不赔付情形。 Erroneously assumes checking a box online waives the written explanation. Replacement rules require that in addition to the declaration form (LIRD), a written explanation (reason-why record) must detail the replacement rationale, new policy advantages, and situations where it might not pay.
看答案与每个选项的解析 Show the answer and why each option is right or wrong 答案 Answer :a
延伸阅读
论坛全文:BC寿险代理人义务2026:KYC、适当性、换保披露该留什么证据
来源
本页知识卡 不看正文也能拿到这一节的核心内容:先看导读,再看图。点图放大,左右翻页。
放大 ⤢ 同一个制度目的,在不同法域落地不同。 先看 先问「哪个省」,再判断落地文件与依据在不同法域怎么写。易漏 数字类问题先问「哪一年」;制度类问题不能用同一个判断方法。下一步 去讲解看第七节陷阱,带「哪个省」的问题找持牌专业人士。详情与分享 → 放大 ⤢ 类型、保额、成本、受益人、条款、演示件要依次处理。 先看 先看哪一步会让首年判断失真,再顺着前后动作读完整条路径。易漏 只比较首年保费会得出错误结论;联合末身故与首身故要看何时需要现金。下一步 去练习按需求持续期做一遍拆分,再带客户目标找持牌专业人士。详情与分享 → 本站依据官方原文自撰 · 出处见正文链接